Author: mdimdadulhaq10@gmail.com

  • Why Prepaid Cards Suit Fixed-Budget Projects: A Setup Guide

    Why Prepaid Cards Suit Fixed-Budget Projects: A Setup Guide

    Example scenario: an agency wins a fixed-fee website project with $2,500 set aside for third-party costs: premium plugins, stock photography, a form tool, a staging server and a small launch ad campaign. Costs go on the agency card. At close-out, the project lead finds $3,400 in related charges, including two plugin renewals nobody cancelled and a staging server still running six weeks after launch. The $900 overrun comes straight out of the agency’s margin.

    Fixed-budget projects fail on the edges. The core work gets tracked closely, while the small external costs drift because they share a card with everything else and keep billing after the project ends. A simple fix is to give the project its own money: load the external-cost budget onto a dedicated prepaid card. This guide explains why that works, how to set it up step by step, and where its limits are.

    What makes prepaid cards different

    A prepaid card spends money that was loaded onto it in advance. It is not linked to a bank account and does not borrow money, which is the key difference from debit and credit cards, as the CFPB’s explainer on prepaid, debit and credit cards describes. For project budgets, that property matters more than any reporting feature: when the project money is gone, the card stops paying.

    Card typeWhere the money comes fromWhat happens at the budget lineProject fit
    Company credit cardBorrowed, repaid laterKeeps paying up to the credit limitOverruns found at month-end
    Company debit cardMain business accountKeeps paying while the account has fundsOverruns hit operating cash
    Prepaid card per projectAmount loaded for the projectDeclines once the loaded balance is usedOverruns are blocked and visible

    Five reasons the budget-to-card method works

    1. The budget becomes physical. The card balance is the remaining budget, visible at a glance.
    2. Overruns require a decision. Adding money is a deliberate step, usually with client or manager approval, instead of a surprise at close-out.
    3. Every charge belongs to the project. Reconciliation is one statement, not a search across company cards.
    4. Renewals stop at close-out. Freeze or empty the card, and forgotten subscriptions fail instead of billing for months.
    5. Contained risk. If a vendor tied to the project has a security problem, only that card’s balance is exposed.

    Step-by-step setup

    1. Split the budget. Separate internal labor from external costs. Only external costs (tools, licenses, media, hosting, contractors’ software) go on the card.
    2. List expected purchases. Write each one with an estimated amount, billing type (one-off or recurring) and currency.
    3. Add a contingency line. Many teams hold back part of the external budget as contingency and load it only when needed.
    4. Get the card and load the approved amount. Name it after the project code in your tracker.
    5. Add the card to each vendor. One person does this, so card details are not passed around.
    6. Track weekly. Compare the card balance with the plan in a five-minute check.
    7. Close out. Cancel recurring tools, freeze the card, reconcile the statement and record any leftover balance.

    Template: project card tracker

    ColumnWhat to record
    Project code and card (last four)Links the card to the project
    Approved external budgetThe total agreed with the client or sponsor
    Amount loadedWhat is on the card now, excluding held contingency
    Planned purchasesItem, estimate, one-off or recurring
    Actual chargesDate, merchant, amount
    Remaining balanceFrom the card dashboard
    Recurring tools to cancelTool, renewal date, cancel-by date
    Change approvalsDate, who approved extra funds, amount
    Close-out statusOpen, closing, closed

    When a prepaid project card is not the right tool

    • Usage-based services with unpredictable bills. If a declined payment would take a live service offline, a hard cap can do more harm than good. Keep those on a payment method with headroom and monitor them closely.
    • Very small projects. If external costs are one or two purchases, a separate card is more admin than it saves.
    • Vendors that refuse prepaid cards. Any merchant can decline a prepaid card. Check the vendor’s payment options before planning around one.
    • Projects where the client pays vendors directly. Then the costs never touch your books at all.

    Close-out checklist

    • Cancel every recurring tool or transfer it to the client’s account.
    • Download the card statement for the project file.
    • Match each charge to a planned purchase or an approved change.
    • Freeze the card so nothing else can charge it.
    • Record the leftover balance and decide whether to reuse the card for the client’s next project or keep it frozen.
    • Note what went over or under plan to improve the next estimate.

    Worked example with Vizovcc

    Vizovcc is one provider that fits this method. It sells prepaid virtual Visa and Mastercard cards that you buy from an account balance funded with crypto, such as USDT, USDC, Bitcoin or ETH. There is no credit line and nothing to repay. Each card has a fixed price shown on its card page, part of which is the issue charge, with the rest loaded onto the card as spendable balance.

    Take the website project above. The agency buys one Vizovcc card sized to the approved external budget and records its last four digits under the project code. The project lead adds it to the plugin store, the stock photo site and the hosting provider. Weekly, they compare the dashboard balance with the plan. At launch plus two weeks, they cancel recurring tools and freeze the card from the dashboard. Any renewal that slipped through the checklist will be declined instead of billed to the agency.

    Some limits apply. Vizovcc has no sub-accounts or team roles, so whoever signs in sees every project’s card, and the login should stay with one person. You cannot set merchant locks or custom spend limits on a card: the loaded balance is the cap. Card balances are not refundable once purchased, so size the card to the budget rather than buying a large card for a small project. Cards are often ready within minutes, and each vendor decides whether it accepts them, so test early in the project, not on launch day.

    Frequently asked questions

    Should each project have its own card, or each client?

    Per project is cleaner for fixed-fee work. Per client suits retainers where costs roll from month to month.

    What if the project needs more money mid-way?

    Treat it as a change request. Get approval, record it in the tracker, then add funds. The extra step is the point.

    Can I reuse a card after the project ends?

    Yes, if it has a leftover balance and the next project is for the same client. Otherwise keep it frozen so old vendors cannot charge it.

    What about projects billed in different currencies?

    Note each vendor’s billing currency in the tracker. If most project costs bill in one currency, a card in that currency avoids conversion on every charge. Check the currency on the card page before buying, and keep a small margin in the balance for any conversion differences.

    Who should hold the card details?

    One person, usually the project lead or the finance owner. They add the card to each vendor directly, so the number never sits in chat threads or shared documents.

    Key takeaways

    • Fixed-budget projects overrun on small external costs that share a company card.
    • A prepaid card loaded with the external budget makes overruns visible and blocks them by default.
    • Track weekly, treat top-ups as change requests, and freeze the card at close-out.
    • Keep usage-based critical services off hard-capped cards.
    • Check vendor acceptance early; any merchant can decline a prepaid card.

    Pick your next fixed-fee project and run its external costs through a dedicated card from kickoff to close-out. If you want a prepaid option funded with crypto, look at Vizovcc and match a card to the project’s approved budget.

  • Virtual Debit, Credit or Prepaid: Which Card to Use Online

    Virtual Debit, Credit or Prepaid: Which Card to Use Online

    Example scenario: you are about to start a $20-a-month design tool. Your bank app offers to create a virtual debit card in seconds. Your credit card issuer has a “virtual number” button too. A colleague swears by prepaid virtual cards for anything that renews automatically. All three would get you through the checkout, but they behave very differently when a charge goes wrong, when a renewal fails or when the merchant gets breached.

    The words “virtual debit” and “virtual credit” are used loosely in marketing, which makes the choice harder than it should be. This guide explains what separates the three card types, compares virtual debit vs credit card protections side by side, and gives you a short framework for deciding which card belongs on which online account.

    The short answer

    “Virtual” only describes the format: a card number, expiry date and security code that live in an app or dashboard instead of on plastic. What matters is where the money comes from.

    • A virtual debit card spends money straight from your bank account.
    • A virtual credit card borrows against a credit line that you repay later.
    • A prepaid virtual card spends a balance you loaded in advance and stops when that balance runs out.

    Everything else, from fraud protection to the effect on your credit file, follows from that difference.

    What each card type is

    Virtual debit card

    A virtual debit card is a second card number linked to your current or checking account. Many banks and neobanks let you create one in their app, sometimes with an option to delete and replace it. Every purchase reduces your account balance immediately, so there is no bill to pay later. The trade-off is that a fraudulent charge also comes out of your real money right away, and you wait for the bank to investigate before it comes back.

    Virtual credit card

    A virtual credit card is a card number tied to a credit card account. Some issuers let you generate extra numbers for online shopping that all bill to the same credit line. You need to qualify for the credit account first, which usually involves a credit check, and you repay what you spend by the due date. As the CFPB’s explainer on prepaid and credit cards puts it, using a credit card means borrowing money, and carrying a balance means paying interest.

    Prepaid virtual card

    A prepaid virtual card is not linked to a bank account or a credit line. You load it with money first, then spend up to that balance. Some prepaid cards can be reloaded and some are used until empty. Because there is no borrowing, there is usually no credit check, and the card cannot take more than what is on it. That same feature can cause a renewal to fail if you forget to keep the balance topped up.

    Virtual debit vs credit vs prepaid: side-by-side comparison

    FeatureVirtual debit cardVirtual credit cardPrepaid virtual card
    Where the money comes fromYour bank accountA credit line you repayA balance you load first
    Usually needsA bank account with that bankCredit approval and a bank account to repay fromFunding for the balance; requirements vary by provider
    Can you spend more than you have?Only if overdraft is enabledYes, up to the credit limitNo, spending stops at the balance
    If a fraudulent charge hitsYour own money is gone until the bank refunds itThe charge sits on the issuer’s money while you dispute itLoss is limited to the balance on that card
    Effect on your credit fileNoneBuilds or harms credit historyNone
    InterestNoneCharged if you carry a balanceNone
    Best online useEveryday purchases from trusted storesLarge purchases, travel bookings, disputes-heavy categoriesSubscriptions, trials, unfamiliar merchants, separate budgets

    A note on fraud rules

    Protection depends on where you live and who issued the card. In the US, federal rules cap your liability for unauthorized credit card charges at $50. Debit card liability depends on how fast you report: up to $50 if you report within two business days, up to $500 after that, and potentially more if you wait beyond 60 days after the statement arrives. Many banks voluntarily offer zero-liability policies on top of this. Since April 2019, the CFPB’s prepaid rule has given many registered prepaid accounts in the US similar error and theft protections. Outside the US, the rules differ by country, and providers often set their own policies, so read the terms before you rely on a card for anything expensive.

    Where each card wins online

    Use a credit card when the purchase is large or risky to deliver

    Flights, hotels, electronics and anything that might not arrive are classic credit card territory. If something goes wrong, the disputed money is the issuer’s, not yours, and you may earn rewards on the purchase. The catch is discipline: interest wipes out any rewards quickly if you do not pay in full.

    Use a debit card for routine purchases from merchants you trust

    A virtual debit card is convenient for regular shopping from established stores. It avoids interest and keeps spending tied to money you have. Avoid putting it on dozens of small sites, because every site that stores the number is another place it can leak from, and a leak hits your main account.

    Use a prepaid card to contain risk and budgets

    Prepaid virtual cards work well for subscriptions you want to cap, free trials you might forget, new merchants you do not fully trust yet and separate budgets such as a project’s tool costs. The worst case is losing the loaded balance, not your salary. They also help people who cannot get a credit card, or whose local bank card is declined by foreign merchants.

    A five-question decision framework

    1. Could this purchase go wrong in a way you would need to dispute? If the amount is large and the delivery is uncertain, lean toward credit.
    2. Will the merchant store your card and charge it again? For recurring billing, a separate prepaid or virtual card limits what a breach or an unwanted renewal can take.
    3. Do you want the spending to stop at a fixed amount? Prepaid cards stop at the balance. Credit and debit cards do not, unless your bank offers spending limits.
    4. Does the merchant accept the card type? Some merchants decline prepaid cards, and some subscription and cloud providers restrict them. Check the merchant’s billing help page before you commit.
    5. Do you need to build credit history? Only a credit card does that. Debit and prepaid cards do not appear on your credit file.

    Three common misconceptions

    • “Virtual credit card” always means credit. Many products sold under that search term are prepaid or debit cards. Check whether there is a credit line, a repayment date and interest. If there is not, it is not a credit card.
    • Virtual cards are always single-use. Some issuers offer disposable numbers, but many virtual cards are ordinary reusable cards that simply have no plastic.
    • A prepaid card is the same as a gift card. Prepaid network cards can often be reloaded and used anywhere the network and merchant accept them. Gift cards are usually tied to one store or ecosystem.

    A prepaid example: how Vizovcc fits

    To see what the prepaid column looks like in practice, take Vizovcc, a service that sells prepaid virtual cards. There is no credit line and nothing to repay. You add crypto such as Bitcoin, USDT, USDC or ETH to an account balance, then buy cards from that balance. Signing up needs an email address, and you do not need a bank account to fund it.

    Each card has a fixed price on its card page, and the page shows how that price splits between a card issue charge and the balance loaded onto the card. Card details appear in the dashboard once the card is ready, often within minutes, though some cards are prepared by the team after purchase. The catalog covers prepaid Visa, Mastercard, American Express, Maestro, JCB and UnionPay cards, including US-issued cards and local-currency cards for a range of countries. Its prepaid Visa and Mastercard virtual cards are the general-purpose options.

    Several features map directly to the prepaid strengths above:

    • Several cards per account from one balance, so subscriptions or projects can each have their own card.
    • Each card has its own balance, which caps what any one merchant can charge.
    • Freeze and unfreeze from the dashboard.
    • 3D Secure support, and card pages that show Apple Pay and Google Pay compatibility.

    The limits matter just as much. Vizovcc funding is crypto only, so it suits people who already hold crypto. Like every prepaid card, acceptance varies: each merchant decides which cards it takes, and any of them can decline a prepaid card. Card purchases are final, so pick the card and currency carefully. And because it is prepaid, it will not build credit history or give you the dispute cushion of a credit card.

    FAQ

    Is a virtual debit card safer than a virtual credit card?

    Not by default. A virtual debit number hides your main card number, but a fraudulent charge still drains your bank account until it is refunded. A credit card keeps the disputed money off your account. A prepaid card limits the loss to its balance.

    Do prepaid virtual cards affect my credit score?

    No. Prepaid cards involve no borrowing, so they are not reported as credit. They neither help nor hurt your credit history.

    Why do some websites decline prepaid cards?

    Merchants set their own payment rules. Some decline prepaid cards to reduce fraud or because they bill in arrears and want a card that can cover a variable bill. Always check the merchant’s payment help page first.

    Key takeaways

    • “Virtual” describes the format. Debit, credit and prepaid describe where the money comes from.
    • Credit cards give the strongest dispute position for large or risky purchases, but cost interest if you carry a balance.
    • Debit cards suit routine purchases from trusted stores, and a leak hits your main account.
    • Prepaid cards cap losses and budgets, which makes them a good fit for subscriptions, trials and new merchants.
    • Check merchant acceptance before you choose a card type for any recurring bill.

    A practical setup for most people is a mix: credit for big purchases, debit for everyday stores and a prepaid card for everything that renews on its own. If you want to try the prepaid side with crypto funding, compare the card pages at Vizovcc and start with one card for your most important subscription.

  • Virtual Card Spend Limits That Let Renewals Through

    Virtual Card Spend Limits That Let Renewals Through

    Here is a typical example. An operations manager gives the design tool a virtual card with a $30 monthly limit, because the plan costs $30. Three months later the vendor adds sales tax at checkout, the renewal comes to $32.40, and the card declines it. The workspace drops to read-only on a Monday morning, two designers lose access to client files, and someone spends an hour finding out why.

    The opposite mistake is just as common. A team sets a generous limit “to be safe”, an annual upgrade goes through by accident, and nobody notices a $600 charge until the statement arrives. A good virtual card spending limit sits between those two failures: high enough that every legitimate renewal clears, low enough that anything unexpected is blocked. This guide explains the limit types providers offer, a simple formula for sizing them, and how to handle a card that has no adjustable limit at all.

    How virtual card limits work

    A spending limit is a rule the card issuer checks when a merchant asks to authorize a payment. If the amount fits inside the rule, the authorization is approved. If it does not, the issuer declines it before any money moves. The merchant only sees a decline, not the reason, which is why a limit that is a little too tight looks to the vendor like a failed card.

    Providers describe their limits differently, so read the details before you rely on one. Privacy.com, for example, lets users set limits per transaction, per month, per year or as a total, and says a transaction that goes over the limit is declined straight away. Other providers reset monthly limits on a calendar date or on a rolling window. That difference matters if your vendor bills on the 30th and the window has not reset yet.

    The main limit types

    Limit typeWhat it blocksBest forWatch out for
    Per-transaction limitAny single charge above the amountFixed-price monthly plansAnnual renewals and one-off seat additions fail
    Monthly (recurring) limitTotal spend above the amount in one periodSubscriptions with occasional add-onsCalendar resets versus rolling windows
    Total or lifetime limitAll spend once the total is reachedTrials, one-off projects, fixed budgetsThe card stops for good when the total is used
    Prepaid balanceAny charge larger than the funds on the cardHard ceilings without settings to manageYou can’t fine-tune it, and renewals fail once funds run low
    Limits inside the platformSpend the platform itself stops or flagsAd accounts, cloud and API usageSome only send alerts and never stop charges

    Limits inside platforms are a separate layer

    Many platforms let you cap spend before it ever reaches the card. Meta’s account spending limit pauses every ad in the account once it is reached, and the amount spent toward it does not reset by itself at month end; you reset it manually, as Meta’s help page on resetting the account spending limit explains. Cloud budgets work differently. According to AWS’s budgeting best practices, the billing data behind AWS Budgets is updated at least once per day, so an alert can arrive after the spend has already happened. A card limit is the backstop behind these tools, not a replacement for them.

    A sizing formula that works for most renewals

    For a fixed-price subscription, set the limit to the plan price, plus any tax the vendor adds, plus a small buffer. Each part covers a specific way renewals fail.

    • Plan price: the amount on your latest invoice, not the price on the marketing page. Seat counts, add-ons and discounts change it.
    • Tax: VAT, GST or sales tax depends on where your business is registered and where the vendor collects tax. Check a real invoice to see whether tax is added on top of the listed price.
    • Currency buffer: if the card is in one currency and the vendor bills in another, the converted amount moves with the exchange rate every month.
    • Price-change buffer: vendors raise prices, usually with notice by email. A buffer gives you one renewal cycle to react instead of a surprise decline.

    Worked example (illustrative numbers): a $20 monthly plan with 20% VAT added at checkout comes to $24. Add a 10% buffer and the limit is about $26.40. Round to $27. A renewal at the normal price clears, a moderate price rise clears, and an accidental annual plan at $240 is blocked.

    Usage-based tools need a different rule

    Cloud hosting, AI APIs and ad platforms bill on usage, so there is no fixed price to start from. For these, base the limit on your highest normal month over the last quarter, add headroom for growth, and set the platform’s own budget alert well below the card limit. The alert tells you spend is climbing. The card limit stops the extreme case, such as a leaked API key or a runaway job.

    Annual plans and verification charges

    Annual renewals are the most common cause of “the limit worked for a year, then failed”. Put a calendar reminder two weeks before each annual renewal and check the limit then. Also expect small verification charges when you first add a card. Google, for example, often places a small charge to check a new card, and it can be declined if the funds or billing details are wrong.

    Step-by-step: setting limits across your subscriptions

    1. Export every recurring charge from the last 12 months of card and bank statements. Note the vendor, amount, currency and billing frequency.
    2. Sort vendors into three groups: fixed monthly, fixed annual and usage-based.
    3. Give each vendor its own card where you can. A limit only makes sense when one card pays one vendor.
    4. Apply the formula to fixed plans: invoice amount, plus tax, plus a 10 to 15% buffer.
    5. Set usage-based limits from your highest recent month plus headroom, and turn on the platform’s own alerts below that line.
    6. Copy billing details exactly as the card provider shows them. A name or address mismatch causes declines that look like limit problems.
    7. Test with the first charge. Watch the first renewal on each new card and adjust before the second one.
    8. Review quarterly. Seat changes and price rises add up, and a limit set a year ago is often wrong today.

    When a renewal still fails

    If a renewal declines, check the cause before raising the limit. Limits are only one of several reasons a card payment fails. Others include an incomplete 3-D Secure check, a billing name or address mismatch, an expired card and the merchant’s own risk checks. Raising a limit to fix a billing-address problem only removes the protection you set up.

    What if your card has no adjustable limit?

    Not every virtual card provider offers spend controls. Some cards are prepaid, which means the ceiling is the money on the card rather than a setting you choose. That is a blunter tool, but it still gives you a hard stop.

    ZenVCC is an example of this model, and it is worth being clear about what it does and doesn’t do. ZenVCC does not offer per-card spend limits, merchant locks or a card freeze. You fund one account balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), then buy separate prepaid Visa, Mastercard, American Express or Maestro cards from that balance. A charge larger than a card can cover is declined as insufficient balance, and cards can’t be topped up from the dashboard, so the prepaid amount is the ceiling.

    Used with the advice above, that structure still covers the main goals:

    • One card per vendor. Each subscription has its own card, so one vendor’s overcharge can’t drain the card paying for another tool.
    • No overspending past the balance. Prepaid funds can’t be exceeded, which suits teams that want a hard stop without managing limit settings.
    • Budgets set inside each platform. ZenVCC leaves budgets to the platforms themselves, which is where the account spending limits and alerts described earlier live.
    • Predictable card costs. Each card has a one-time $10 issue fee, each payment costs $0.10, and there is no monthly fee.
    • Fewer card swaps. Cards are valid for three years from the day they are ready, and if a card can’t be prepared, the full amount, issue fee included, goes back to your balance.

    The trade-off is flexibility. If you need to raise a limit by a few dollars before tomorrow’s renewal, a card with adjustable controls is easier. If a prepaid card is running low ahead of a renewal, plan to move that vendor to a new card in time. The cards also can’t complete a payment that asks for a 3-D Secure code, because the dashboard doesn’t show those codes, so check whether a vendor requires that step. ZenVCC’s guide to why card payments get declined covers the common causes and what to check first.

    Common mistakes

    • Setting the limit to the exact list price. Tax, currency movement and price changes push real charges above it.
    • Sharing one limited card across several vendors. The first vendor to bill uses up the room, and the others decline.
    • Forgetting annual renewals. A monthly-sized limit will block the yearly charge.
    • Relying on platform alerts alone. An alert that arrives the next day does not stop a charge that already happened.
    • Using limits to avoid a vendor’s terms. A declined renewal does not cancel a contract. Cancel inside the vendor’s account, and treat the card limit as a safety net.

    Key takeaways

    • Size fixed-plan limits as invoice amount plus tax plus a 10 to 15% buffer.
    • Base usage-based limits on your highest normal month, with platform alerts set below the card limit.
    • One card per vendor is what makes any limit useful.
    • Check annual renewals and verification charges before they hit.
    • A prepaid card works as a fixed ceiling even when there is no limit setting to adjust.

    Start with your five most expensive subscriptions this week: put each on its own card, apply the formula and note the next renewal dates. If you prefer prepaid cards with no monthly fee as the ceiling behind your platform budgets, take a look at ZenVCC and see whether its model fits your stack.

  • Paying Your Shopify Plan and Apps With a Virtual Card: A Store Owner’s Billing Guide

    Paying Your Shopify Plan and Apps With a Virtual Card: A Store Owner’s Billing Guide

    Your Shopify bill failed, the admin shows a payment warning, and your local bank card won’t process an international charge. A virtual card looks like the obvious fix. Before you try, read Shopify’s own rule: its help center says prepaid and virtual credit cards aren’t accepted for paying Shopify bills. This guide explains what is on the bill, what Shopify does accept, how to keep the store from being frozen, and where a separate virtual card still makes sense in a store’s finances.

    Quick answer

    – Your plan, Shopify-billed apps and shipping labels are paid through the Shopify bill, and Shopify doesn’t accept prepaid or virtual cards for it.

    – Use one of Shopify’s listed methods: a credit card or co-branded debit card with recurring international payments enabled, PayPal, Shopify Balance, or a local method where offered.

    – A virtual card is still useful for tools billed outside Shopify, such as SaaS, design tools and some ad platforms, subject to each vendor’s rules.

    What goes on your Shopify bill

    Shopify collects several kinds of charges on one bill, and they all use the payment method in Settings > Billing:

    • Your subscription plan, billed monthly or annually.
    • App charges for apps that bill through Shopify. Recurring app fees and one-off or usage charges appear on the Shopify bill, not on separate card charges from each developer.
    • Shipping labels bought in Shopify, which Shopify’s help center says use a threshold billing system, so they are charged when your label spend reaches a threshold or at the end of the cycle.
    • Themes, domains bought through Shopify and other Shopify services.

    This matters because it means you can’t pay “just the apps” with a different card. If an app bills through Shopify, it is paid by your Shopify billing method. [VERIFY: Shopify’s current billing cycle and threshold rules for each charge type]

    What Shopify accepts, and what it doesn’t

    Shopify’s help page on payment methods for bills lists the options. Availability depends on your store’s region and billing currency:

    • Credit cards and co-branded debit cards from Mastercard, Visa, American Express, Diners Club or Discover, with recurring payments enabled on the card and some country-specific exclusions.
    • Shopify Balance in supported regions.
    • PayPal, which is not available in India or in some billing currencies.
    • Apple Pay or Google Pay on some plans and countries.
    • Bank debits: ACH for US stores with a USD bank account, SEPA Direct Debit for eligible European stores, UPI for India.
    • Revolut Pay for eligible European stores billing in EUR, DKK or PLN.

    The same page states plainly: “Prepaid and virtual credit cards aren’t accepted.” A prepaid virtual card might get through once, but it is outside Shopify’s terms for billing and you should expect it to fail. A store that depends on a payment method the platform says it doesn’t accept is a store at risk of being frozen.

    Why Shopify bill payments fail

    CauseWhat’s happeningFix
    Card not enabled for international or recurring paymentsYour bank declines a foreign recurring chargeAsk your bank to enable both, or use another listed method
    Billing currency mismatchThe card can’t process the currency your bill usesShopify’s troubleshooting asks that the card processes recurring international charges in USD or a supported local currency; change the billing currency where allowed
    Prepaid or virtual cardNot accepted under Shopify’s billing rulesSwitch to a listed method
    3D Secure not completedThe issuer requires authenticationComplete the 3DS step; Shopify says payment attempts retry automatically until verification is complete
    Insufficient funds or limitThe issuer declines the amountFund the account or raise the limit, then use Pay bill in Settings > Billing
    Repeated failed SEPA debitsThe bank may block the mandateFix the cause before the next attempt

    The most common case for store owners outside the US and EU is the first one. Many local debit cards are set up for domestic payments only. A call to the bank to enable international e-commerce and recurring payments often fixes the problem without changing anything at Shopify.

    If the bank can’t or won’t enable international recurring charges, look at the other listed methods before anything else. PayPal linked to a local account, Shopify Balance where it is offered, or a bank debit in your region all avoid the card question entirely. Changing the billing currency, where Shopify allows it for your region, can also help when your card handles one currency but not another. Each of these stays inside Shopify’s rules, which a prepaid card does not.

    How to keep your store from being frozen

    If bills remain unpaid, Shopify can freeze the store, and a frozen store has to be reactivated by paying the outstanding bill. [VERIFY: Shopify’s current timeline from failed payment to frozen store] The routine below keeps you clear of that.

    1.  Pick a listed payment method that suits your region and currency, and test it with your next bill.

    2.  Enable recurring and international payments on the card with your bank, or set up PayPal or a bank debit if available.

    3.  Add a backup method where Shopify allows one, so one decline doesn’t stop billing.

    4.  Check Settings > Billing weekly during your first months. App usage charges and shipping labels can make the bill bigger than the plan price.

    5.  Review installed apps every month. Uninstall apps you no longer use. Their recurring charges stay on the bill until you remove them. [VERIFY: whether uninstalling ends app charges immediately or at the end of the cycle]

    6.  Fix a failed payment the same day with Pay bill, rather than waiting for automatic retries.

    7.  Keep invoices from Settings > Billing for your accounts and tax records.

    Where a virtual card does help a Shopify store

    The Shopify bill is only part of what a store spends. Most stores also pay for tools that bill you directly, outside Shopify:

    • Email, SMS and review platforms that bill on their own website rather than through the Shopify App Store.
    • Design and productivity tools such as image editors, stock photo libraries and project management software.
    • Domain registrars and hosting for domains not bought through Shopify.
    • Ad platforms, each with its own payment rules. Google’s help center, for example, says prepaid cards are not accepted for postpay billing in Google Ads, so check each platform’s policy first.

    For these, a card per vendor makes the books easier: every charge on a card belongs to one tool, a renewal can’t surprise you, and a card can be frozen when you stop using the tool. Each vendor sets its own rules on prepaid cards, so check before you subscribe.

    One example is VCCBuy’s Shopify page, which covers this kind of store tool spending. VCCBuy issues prepaid Visa and Mastercard cards funded with USDT, USDC and other supported coins, with balances credited in USD after deposits are checked. Each card can be renamed for the tool it pays, frozen and unfrozen, and given its own billing address, and 3D Secure codes are requested in the dashboard and shown for 10 minutes. To be clear, these cards are prepaid, so they are not a way to pay the Shopify bill itself. Bank-issued virtual cards and expense cards work the same way for outside tools.

    FAQ

    Can I pay my Shopify plan with a prepaid or virtual card? Shopify’s help center says prepaid and virtual credit cards aren’t accepted for Shopify bills. Use a credit card or co-branded debit card with recurring payments enabled, PayPal, Shopify Balance or a local method listed for your region.

    Can I pay Shopify apps with a different card from my plan? Not for apps that bill through Shopify. Their charges go on your Shopify bill and use your Shopify billing method. Tools that bill you directly on their own websites can use any card they accept.

    What happens if my Shopify payment fails? Fix the cause and use Pay bill in Settings > Billing. For 3D Secure, Shopify retries automatically once you authenticate. If bills stay unpaid, the store can be frozen until the balance is paid.

    Conclusion

    Shopify’s bill has clear rules: listed payment methods only, with recurring and international payments enabled, and no prepaid or virtual cards. Set that up properly, review apps monthly and fix failures the same day. For the tools you pay outside Shopify, a card per vendor keeps spending visible, and VCCBuy is one option to compare with bank-issued virtual cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about platform billing rules and how online store owners keep tool spending under control.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Cloud Bill Shock: How Developers Cap AWS, GCP and Vercel Costs Before They Explode

    Cloud Bill Shock: How Developers Cap AWS, GCP and Vercel Costs Before They Explode

    You set up a side project, forgot a NAT gateway or a GPU instance, and the monthly bill arrived at ten times your estimate. Or a viral post sent traffic to a serverless app and the bandwidth line went vertical. You did set a budget. It sent an email. It didn’t stop anything.

    Quick answer

    1. On AWS and GCP a budget is an alert, not a cap. To stop spending, you have to attach an action (AWS) or automation (GCP).

    2. Vercel can pause production deployments when a spend amount is reached, if you turn that on.

    3. A prepaid card is a funding ceiling, not a usage cap. On pay-as-you-go cloud it limits what is charged at one time, but a decline doesn’t cancel the bill.

    Why cloud bills explode

    Cloud billing is metered and charged in arrears. You use resources now, the provider meters them, and the card is charged later, usually monthly. Three properties make that dangerous:

    • No natural stop. Unless you configure one, the platform keeps serving requests and running instances, because stopping would break production for most customers.
    • Billing data lags. Cost data reaches dashboards and budgets hours after the usage. Google’s documentation on disabling billing from budget notifications warns that its own example doesn’t guarantee you won’t spend more than your budget, and recommends setting the budget below your available funds to allow for delays.
    • Costs hide in side lines. Data transfer, NAT gateways, idle load balancers, log ingestion, snapshots and egress rarely show up in the first estimate.

    What each platform can actually stop

    PlatformAlertAutomatic stopWhat the stop doesWatch out for
    AWSBudgets (cost, usage, forecast) and Cost Anomaly DetectionBudgets actions: apply an IAM policy or SCP, or stop specific EC2 or RDS instancesBlocks new resource creation or stops named instancesDoesn’t touch S3, data transfer or managed services you didn’t target; EC2/RDS actions don’t reset automatically
    GCPBudgets with threshold alertsNo built-in stop; budget notifications to Pub/Sub can trigger a function that disables billing on the projectDisabling billing terminates all services in the project, including Free TierDelay between usage and budget data; not a guaranteed cap
    GCPQuotas per APIRequests above the quota are refusedLimits volume for that APIPer service, not a project-wide dollar cap
    Vercel (Pro)Spend Management notificationsPause production deployment when the spend amount is reachedAll projects on the team are paused; visitors get 503 DEPLOYMENT_PAUSEDRaising the limit doesn’t unpause; each project has to be resumed manually

    AWS: budgets plus actions

    AWS Budgets lets you set cost and usage budgets, with alerts on actual or forecast spend. Budgets actions go further: when a threshold is crossed, AWS can apply an IAM policy or a service control policy (for example, one that denies launching new instances), or stop specific EC2 or RDS instances. You can run actions automatically or require approval.

    Two caveats. An action only does what you target: stopping an EC2 instance doesn’t delete the EBS volumes, Elastic IPs or snapshots that keep costing money. And instance-targeted actions don’t reset each period, so check them after they fire. Cost Anomaly Detection is worth enabling alongside, because it flags unusual patterns before a monthly threshold is reached.

    GCP: alerts, then your own automation

    A Google Cloud budget sends notifications. It doesn’t stop usage by itself. Google documents a pattern where budget notifications go to a Pub/Sub topic and a Cloud Function disables billing on the project when costs pass the budget.

    That works as a last resort, but read the warning: disabling billing terminates all Google Cloud services in the project, and some resources may be removed if billing stays disabled. [VERIFY: current wording on resource deletion in Google Cloud’s “Disable billing usage with notifications” page] Use it on sandboxes and experiments, not on a production project with data you need. For production, use quotas on expensive APIs and alerts at 50%, 80% and 100%.

    Vercel: a real spend stop, with manual restart

    Vercel’s Spend Management (on Pro teams) lets you set a spend amount and turn on pause production deployment. When the team reaches it, Vercel pauses production for every project on the team, and visitors see a 503 DEPLOYMENT_PAUSED error. Raising the amount doesn’t bring the projects back. You resume each one from the dashboard or the REST API. A webhook can fire on spend events, so you can alert a channel or switch to a static fallback.

    That is closer to a true cap than AWS or GCP give you by default. The cost is downtime, so decide in advance which projects can afford it.

    A cost-cap procedure for a new account

    1.  Turn on alerts on day one. Budget at your expected monthly spend, with alerts at 50%, 80% and 100% of actual and at 100% of forecast.

    2.  Add the stop. AWS: a Budgets action that applies a deny policy on new resource creation at, say, 120% of budget. GCP sandboxes: the Pub/Sub disable-billing function. Vercel: pause production at your hard limit.

    3.  Set quotas on expensive APIs and services (GPUs, AI APIs, maps and similar).

    4.  Tag everything by project and owner so the bill can be traced.

    5.  Schedule a weekly five-minute review of the cost explorer, sorted by service, looking for anything you don’t recognize.

    6.  Delete, don’t just stop. After experiments, remove volumes, IPs, snapshots and load balancers.

    7.  Set a funding ceiling on the payment method, as described below.

    Where a funding ceiling helps, and where it doesn’t

    Developers often ask whether paying with a prepaid card caps the bill. The honest answer: partly.

    What a prepaid card does:

    • It limits what can be charged at one time to the balance on the card. Nothing is borrowed.
    • It turns each top-up into a review point: you look at the cost dashboard before you add funds.
    • It contains the damage from a stolen or misused card number to that one card.

    What it doesn’t do:

    • It doesn’t stop usage. AWS, GCP and Vercel meter usage first and charge later. A declined charge doesn’t cancel the bill. The provider will retry, send reminders, and can suspend or close the account until you pay what you owe.
    • It doesn’t replace the platform controls above. Those act on usage; the card acts only on payment.

    Also check acceptance before you rely on one. AWS checks a new card with an authorization of about $1 that is later released, according to AWS re:Post, so the card needs a balance to pass. Some platforms don’t accept prepaid cards at all; users on the Railway forum, for example, report that many prepaid cards are disabled there.

    A crypto-funded option

    If your revenue arrives in stablecoins, or you want cloud spend kept apart from your personal or company credit card, a crypto-funded prepaid card is one way to build that ceiling. As one example, VCCBuy’s cards for SaaS and cloud are prepaid Visa and Mastercard cards funded with USDT, USDC and other coins and held in USD. Each card can be frozen and unfrozen, renamed per project, and has its own billing name and address and transaction list. There is no monthly fee; there is a card issue fee and a 2–3% top-up fee depending on the card.

    The limits: VCCBuy is not a bank, its cards are prepaid, and any provider can decline prepaid cards. Bank-issued virtual cards with spend limits are a common alternative.

    FAQ

    Does an AWS budget stop my resources when I hit it? Not on its own. A budget sends alerts. To stop or block resources, attach a Budgets action, such as an IAM policy that denies new launches or an action that stops named EC2 or RDS instances.

    If my card is declined, does the cloud provider stop charging me? No. Usage is billed after it happens, so the amount is still owed. The provider will retry and may suspend the account until it is paid. Use platform controls to stop usage.

    What’s the safest way to cap a side project? Combine a budget with an automatic action, quotas on expensive services, and a dedicated payment card with a modest balance. On GCP sandboxes, the Pub/Sub disable-billing pattern is a hard stop, but it shuts down everything in the project.

    Conclusion

    Cloud bills explode because metering never stops on its own and billing data arrives late. Pair alerts with real actions on AWS, automation or quotas on GCP and the pause setting on Vercel, then put a funding ceiling on the card as the last line. If you want that ceiling funded from stablecoins, VCCBuy is one option to compare with your bank’s virtual cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about cloud and SaaS billing, and the limits developers can set before an invoice arrives.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP CPI Integration with REST and SOAP APIs

    SAP CPI Integration with REST and SOAP APIs

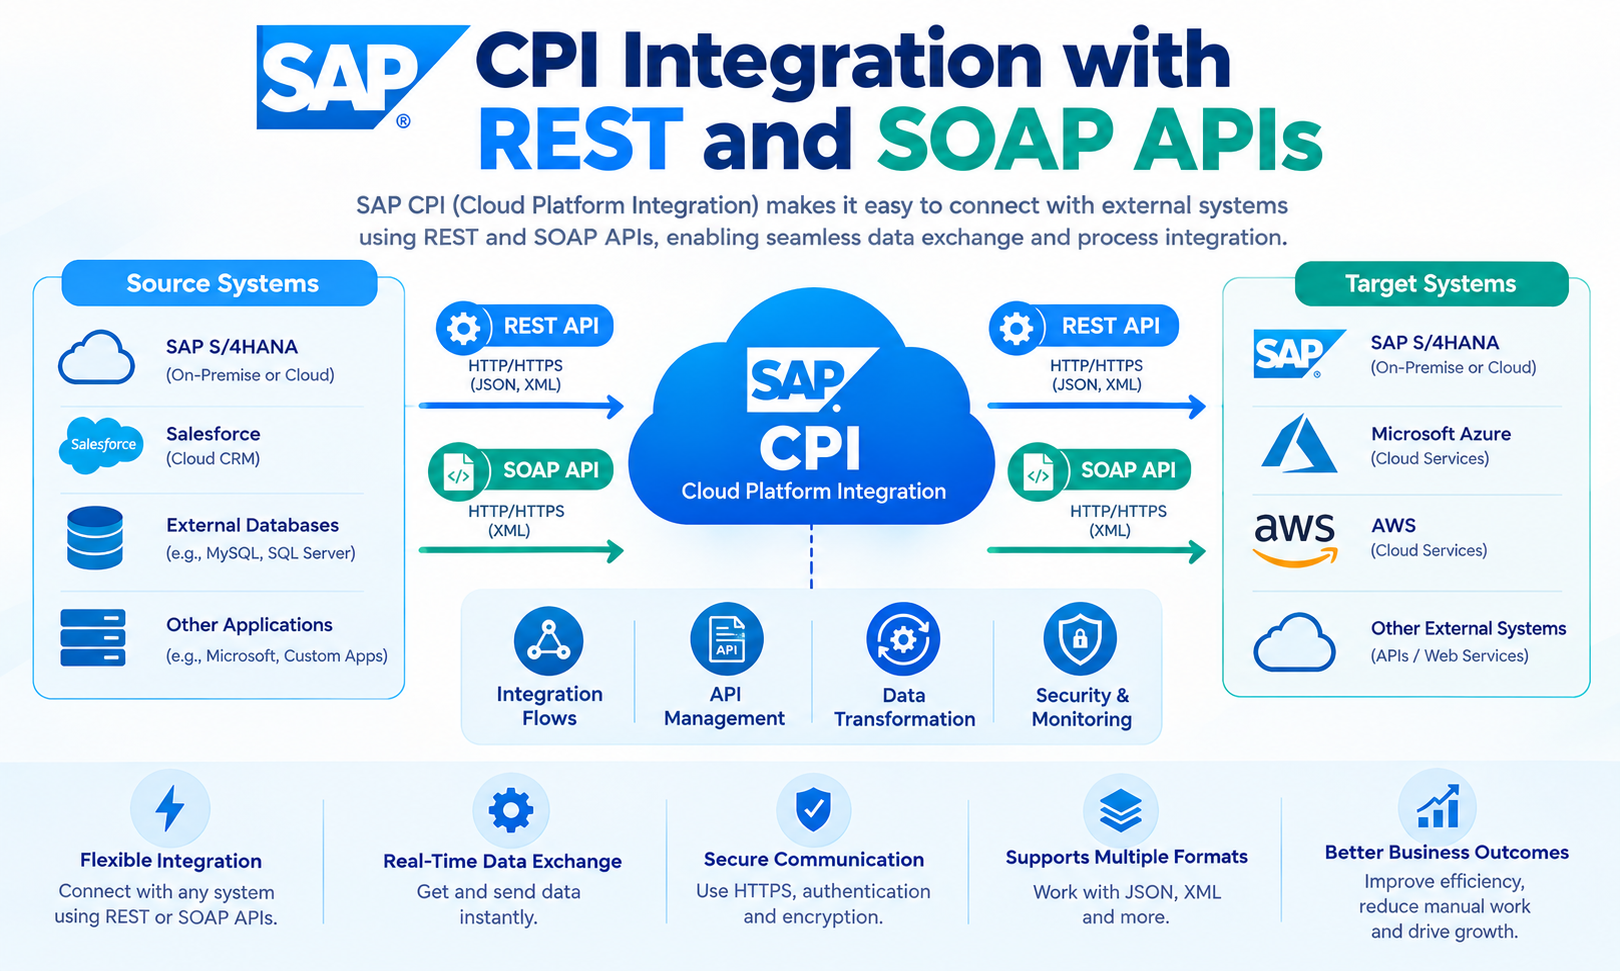
    SAP CPI Integration is widely used to connect SAP and non-SAP applications through APIs and integration flows. REST and SOAP are two important API technologies supported by SAP Cloud Integration, which is the Cloud Integration capability within SAP Integration Suite on SAP Business Technology Platform (SAP BTP). These technologies allow organizations to exchange business data between cloud applications, on-premise systems, web services, and enterprise applications.

    REST and SOAP use different communication models, message structures, and technical standards. SAP Cloud Integration provides tools and adapters that help integration developers receive, process, transform, and send these messages between connected systems. SAP documentation identifies REST and SOAP as supported API-based integration approaches in Cloud Integration.

    What Is SAP CPI Integration?

    SAP CPI Integration refers to the use of SAP Cloud Integration to connect applications, systems, APIs, and business processes. SAP Cloud Integration runs as part of SAP Integration Suite on SAP BTP. It provides a cloud-based environment where developers can create, deploy, and monitor integration flows.

    An integration flow, commonly called an iFlow, defines how a message moves from a sender to a receiver. The flow can receive a request, validate information, transform the message, apply routing logic, and send the result to another system.

    SAP Cloud Integration can exchange data between cloud and on-premise systems. SAP documentation states that sender and receiver systems can reside in cloud or on-premise environments when using the standard cloud deployment model.

    REST and SOAP in SAP CPI Integration

    REST and SOAP are different technologies for exchanging information between applications.

    REST, or Representational State Transfer, commonly uses HTTP-based communication. REST APIs can work with methods such as GET, POST, PUT, and DELETE, depending on the API design. JSON is widely used for REST API payloads, although REST can support other formats.

    SOAP, or Simple Object Access Protocol, is a protocol for structured web service communication. SOAP messages commonly use XML and can use Web Services Description Language (WSDL) to describe service operations and message structures.

    SAP Cloud Integration supports API-based integration development for REST and SOAP services. SAP documentation identifies REST API artifacts with the HTTPS sender adapter and SOAP API artifacts with the SOAP 1.x sender adapter.

    How REST APIs Work with SAP CPI Integration

    A REST-based integration can use SAP Cloud Integration as an intermediary between applications.

    For example, an e-commerce application may send a customer order through a REST API. SAP Cloud Integration can receive the request, validate the payload, transform the data, and forward it to an SAP system.

    A simplified flow can look like this:

    REST Client → SAP Cloud Integration → Transformation → SAP or Non-SAP System

    The HTTPS adapter is used for REST-based API scenarios in Cloud Integration. SAP documentation identifies HTTPS as the protocol type associated with REST service endpoints.

    The integration flow can process information such as:

    Customer ID
    Product ID
    Quantity
    Price
    Order number
    Shipping information
    Payment status

    The exact data structure depends on the API contract and the connected business systems.

    How SOAP APIs Work with SAP CPI Integration

    SOAP-based integration uses structured XML messages and web service definitions. SAP Cloud Integration provides SOAP sender and receiver capabilities for SOAP-based communication.

    A SOAP integration can receive a request from an external application, process the message, and forward it to another SOAP service. It can also receive information from a SOAP service and transform it for another application.

    SAP documentation shows that the SOAP sender adapter can expose an endpoint for an integration flow. It can also use a WSDL to define the message structure. The SOAP adapter supports SOAP 1.x communication, including SOAP 1.1 and SOAP 1.2 in the documented SOAP sender scenario.

    A basic SOAP flow can look like:

    SOAP Client → SAP Cloud Integration → Message Processing → SOAP Service

    SOAP is commonly encountered in enterprise environments where existing applications expose web services based on XML and WSDL.

    REST API Integration Flow in SAP Cloud Integration

    A REST integration flow usually begins with an HTTPS sender endpoint.

    The integration developer creates an integration package and adds the required API or integration flow. For a REST API artifact, SAP documentation describes the use of the Cloud Integration runtime profile and REST API type.

    The flow can then contain processing steps such as message transformation, content modification, routing, validation, and receiver communication.

    For example:

    Mobile Application → REST API → SAP Cloud Integration → SAP S/4HANA

    The mobile application sends a request. Cloud Integration receives it through the API endpoint. The integration flow processes the request and sends the required data to the target SAP system.

    The response can then travel back through the integration flow to the original application when the scenario is designed for request-response communication.

    SOAP API Integration Flow in SAP Cloud Integration

    A SOAP integration flow uses the SOAP adapter to communicate with SOAP-based systems.

    The sender channel defines how the external application calls the integration flow. SAP documentation describes parameters such as the endpoint address, service definition, and message exchange pattern when configuring a SOAP sender channel.

    A SOAP integration may use a WSDL to describe the service interface. The WSDL can define operations, messages, and service-related information used by the client and integration design.

    A common enterprise flow could be:

    Legacy ERP → SOAP → SAP Cloud Integration → REST API → Cloud Application

    This allows an older SOAP-based application to exchange information with a newer REST-based application.

    REST to SOAP Integration with SAP CPI

    One important use of SAP CPI Integration is connecting systems that use different API technologies.

    A source application may provide a REST API while the target application requires SOAP. Cloud Integration can act as the integration layer between them.

    For example:

    REST Application → HTTPS → SAP Cloud Integration → SOAP → Enterprise System

    The integration flow can receive a JSON request from the REST application. It can then transform the data into the XML structure required by the SOAP service.

    The SOAP receiver sends the transformed request to the target system. The response can be converted back into the format expected by the REST application.

    This approach avoids requiring both applications to use the same API technology.

    SOAP to REST Integration with SAP CPI

    The reverse scenario is also possible.

    An existing SOAP application may need to communicate with a modern REST-based application. SAP Cloud Integration can receive the SOAP request and convert the information into a REST-compatible request.

    The general flow can be:

    SOAP Application → SAP Cloud Integration → XML-to-JSON Transformation → REST API

    The exact transformation depends on the source and target schemas.

    For example, a SOAP message containing customer information may include XML elements such as customer ID, name, email address, and telephone number. The integration flow can map these fields into a JSON structure required by the REST API.

    Message Transformation in SAP CPI Integration

    Message transformation is an important part of API integration.

    REST services commonly use JSON, while SOAP services commonly use XML. A connected system may also use CSV, plain text, IDoc, or another structured format.

    SAP Cloud Integration provides integration capabilities for processing and transforming messages. The integration flow can apply mapping and other processing steps before the message reaches the receiver.

    For example:

    REST JSON

       ↓

    SAP Cloud Integration

       ↓

    Message Mapping

       ↓

    XML

       ↓

    SOAP Service

    The mapping process can rename fields, change data structures, convert values, and organize information according to the target system’s requirements.

    JSON and XML Processing

    REST integrations frequently use JSON payloads. JSON is a text-based data format that represents information through objects, arrays, names, and values.

    SOAP services generally use XML-based messages. XML provides a structured format that can represent complex business information.

    SAP CPI Integration can therefore serve as a conversion layer between JSON-based REST services and XML-based SOAP services.

    For example, a REST request might contain:

    {

      “customerId”: “10025”,

      “orderId”: “50001”,

      “amount”: 250

    }

    The integration flow can transform this information into an XML structure required by a SOAP service.

    The actual transformation depends on the target service contract.

    Authentication and Security

    API security is an important part of SAP Cloud Integration design.

    The authentication method depends on the sender, receiver, API, adapter, and security requirements. Cloud Integration provides configuration options for communication with external services.

    For SOAP services, security can also involve WSDL definitions and SOAP-specific security requirements. SAP documentation for SOAP receiver scenarios includes authentication, transport settings, and WS-Security configuration options for applicable API artifacts.

    For REST services, authentication can depend on the API provider. Common approaches can include credentials, certificates, OAuth-based mechanisms, or other supported authentication models.

    Security settings should match the requirements of the connected systems and the organization’s security policies.

    API Endpoints in SAP Cloud Integration

    An API endpoint is the address through which a system communicates with an integration service.

    For REST-based integration, the HTTPS endpoint is used for the REST API scenario. SAP documentation states that REST API artifacts use the HTTPS sender adapter.

    For SOAP-based integration, the SOAP sender adapter provides the endpoint used by the calling system. SAP documentation shows that the endpoint address can be configured when creating a SOAP sender channel.

    SAP also provides service endpoint information for Cloud Integration. Its documentation identifies protocol types such as SOAP and REST for supported service endpoints.

    SAP CPI Integration with Cloud and On-Premise Systems

    SAP CPI Integration can connect cloud applications with on-premise applications.

    For example:

    Cloud CRM → REST → SAP Cloud Integration → SOAP → On-Premise ERP

    The cloud application sends information to the integration layer. Cloud Integration processes the message and sends it to the on-premise system.

    Depending on the network architecture and scenario, SAP connectivity components such as SAP Cloud Connector can be used to establish secure access to on-premise systems.

    The specific connectivity setup depends on the deployment model, system location, and communication requirements.

    SAP documentation confirms that SAP Integration Suite can exchange data with both cloud and on-premise applications.

    Error Handling in REST and SOAP Integration

    API integrations must account for communication and processing errors.

    Possible issues include:

    Incorrect endpoint URL
    Authentication failure
    Invalid JSON
    Invalid XML
    Missing required fields
    Schema mismatch
    Timeout
    Unavailable receiver system
    Incorrect API method
    Application-level error

    An integration flow can use error-handling mechanisms to identify and process failed messages.

    For example, a failed REST request may return an HTTP error response. A SOAP service may return a SOAP fault containing information about the failure.

    The integration design should define how errors are logged, reported, retried, or returned to the calling application.

    Monitoring SAP CPI Integration

    Monitoring helps integration teams examine the execution of deployed integration content.

    A typical monitoring process includes checking message processing, identifying failed messages, reviewing error information, and examining communication between systems.

    SAP Cloud Integration supports integration artifacts such as integration flows, REST APIs, SOAP APIs, OData APIs, value mappings, and integration adapters.

    Monitoring becomes particularly important when an integration connects multiple systems. A failure in one endpoint can affect the complete business process.

    REST API vs SOAP API in SAP CPI Integration

    REST and SOAP solve different integration requirements.

    FeatureRESTSOAP
    Common message formatJSON, XMLXML
    Main communication styleHTTP-basedSOAP web service
    Service descriptionAPI specification can be usedWSDL commonly used
    Common useWeb and cloud APIsEnterprise and legacy web services
    Cloud Integration supportHTTPS/REST APISOAP adapter/SOAP API
    Message structureGenerally lightweightStructured XML envelope
    SAP CPI Integration useAPI and application connectivityEnterprise web service connectivity

    The appropriate approach depends on the source system, target system, API contract, security requirements, and business process.

    Practical Example of SAP CPI Integration with REST and SOAP

    Consider an online store that uses a REST API while its internal ERP system exposes a SOAP service.

    The online store sends an order using JSON:

    Customer: 10025

    Product: P100

    Quantity: 2

    Amount: 250

    SAP Cloud Integration receives the request through an HTTPS endpoint.

    The integration flow validates the information. It then maps the JSON data into the XML structure required by the ERP SOAP service.

    The SOAP receiver sends the XML message to the ERP system.

    The ERP system processes the order and returns a response. Cloud Integration can process the response and return an appropriate response to the REST application.

    This architecture allows the two systems to communicate without requiring the online store to implement the ERP system’s SOAP interface directly.

    Best Practices for REST and SOAP Integration

    A reliable integration design starts with a clear interface contract. The source and target systems should define the required fields, data types, operations, authentication methods, and response structures.

    Integration flows should use clear names and logical processing steps. SAP documentation provides naming guidance for API-based integration development and recommends structured naming for integration packages and APIs.

    Security credentials should not be exposed in message payloads or source code. Endpoint configuration should also be separated from business transformation logic where appropriate.

    Error handling should be designed before deployment. The integration should define what happens when a receiver is unavailable or when the incoming message does not meet the expected structure.

    Testing should include valid requests, invalid requests, authentication failures, unavailable systems, incorrect data types, and error responses.

    AEO for SAP CPI Integration with REST and SOAP APIs

    Answer Engine Optimization, or AEO, focuses on creating content that directly answers questions users ask in search engines and AI-powered answer systems.

    For this topic, useful questions include:

    What is SAP CPI Integration?

    How does SAP CPI connect REST and SOAP APIs?

    Can SAP Cloud Integration convert REST to SOAP?

    Does SAP Cloud Integration support REST APIs?

    Does SAP Cloud Integration support SOAP APIs?

    How does JSON convert to XML in an integration flow?

    A clear page structure helps answer these questions. Short definitions, direct explanations, tables, examples, and FAQs make the information easier for search and answer systems to process.

    GEO for SAP CPI Integration

    Generative Engine Optimization, or GEO, focuses on making technical information clear and useful for AI-generated search responses.

    For SAP CPI Integration content, important entities include SAP Cloud Integration, SAP Integration Suite, SAP BTP, REST API, SOAP API, HTTPS, XML, JSON, WSDL, API endpoints, integration flows, and message mapping.

    The content should connect these entities through factual relationships. For example, SAP Cloud Integration is a capability within SAP Integration Suite, while REST API artifacts can use the HTTPS sender adapter and SOAP scenarios can use SOAP adapters.

    Using precise terminology helps reduce ambiguity. The term SAP CPI is still widely used, while current SAP documentation commonly refers to the capability as Cloud Integration within SAP Integration Suite.

    Frequently Asked Questions

    What is SAP CPI Integration?

    SAP CPI Integration is the use of SAP Cloud Integration to connect applications, APIs, and business systems. It can process, transform, route, and exchange messages between connected systems.

    Does SAP Cloud Integration support REST APIs?

    Yes. SAP Cloud Integration supports REST API-based integration scenarios. SAP documentation describes REST API artifacts using the HTTPS sender adapter.

    Does SAP Cloud Integration support SOAP APIs?

    Yes. Cloud Integration supports SOAP-based integration. SOAP sender and receiver adapters can be configured for communication with SOAP web services.

    Can SAP CPI Integration connect REST and SOAP systems?

    Yes. An integration flow can connect systems that use different communication technologies. For example, a REST client can send JSON to Cloud Integration, where the data can be transformed before being sent to a SOAP service.

    Can REST JSON be converted to SOAP XML?

    Yes. An integration flow can process a JSON REST request and transform the information into an XML structure required by a SOAP service. The exact mapping depends on the source and target message structures.

    What is WSDL in SOAP integration?

    WSDL, or Web Services Description Language, describes a SOAP web service. It can define service operations, messages, and related interface information. Cloud Integration supports WSDL-based configuration for applicable SOAP scenarios.

    What is an HTTPS adapter in SAP Cloud Integration?

    The HTTPS adapter can be used for HTTP-based communication. SAP identifies HTTPS as the protocol type for REST service endpoints in Cloud Integration.

    Can SAP CPI Integration connect cloud and on-premise systems?

    Yes. SAP Integration Suite can exchange data with cloud and on-premise applications. The exact connectivity architecture depends on the systems and deployment scenario.

    What is the difference between REST and SOAP?

    REST commonly uses HTTP-based API communication and often uses JSON. SOAP is a structured web service protocol that commonly uses XML and WSDL. Both can be used in enterprise integration scenarios, but their interfaces and message models are different.

    Conclusion

    SAP CPI Integration provides a cloud-based approach for connecting applications and business systems through integration flows and APIs. REST and SOAP are important technologies for these scenarios. REST commonly supports modern API communication, while SOAP remains important for structured web services and existing enterprise applications.

    SAP Cloud Integration can process messages, transform data, connect different endpoints, and support communication between cloud and on-premise systems. REST-to-SOAP and SOAP-to-REST scenarios can also be implemented when applications use different API technologies.

    A well-designed integration requires clear API contracts, suitable adapters, appropriate security, accurate message mapping, error handling, testing, and monitoring. These elements help create maintainable integrations between SAP and non-SAP systems.

  • Corporate Travel and Expense: The Case for API-Issued Employee Cards

    Corporate Travel and Expense: The Case for API-Issued Employee Cards

    Corporate travel and expense programs often fail at the points where policy, payment, and reporting should align. Manual reimbursements, shared cards, and disconnected approval flows create avoidable risk and friction. API-issued employee cards offer a more controlled model by embedding spend rules directly into each transaction. The result is not simply faster processing, but a structural shift in how organizations manage travel spend—and its implications extend further than many teams expect.

    Why T&E Processes Break Down

    Breakdowns in travel and expense (T&E) processes typically arise when organizations rely on fragmented workflows, inconsistent policy enforcement, and manual data handling.

    These conditions create T&E inefficiencies that weaken Budget oversight and introduce Compliance challenges across departments. Process bottlenecks emerge when approvals depend on multiple stakeholders, causing Approval delays and limiting timely reimbursement.

    Manual tracking increases the likelihood of Data inaccuracies, duplicate entries, and incomplete documentation. Communication gaps between finance teams, managers, and travelers further complicate reconciliation and reporting.

    Policy misunderstandings often result from unclear guidelines or inconsistent interpretation, producing exceptions that require additional review. As administrative burdens accumulate, Employee frustration rises, and operational visibility declines.

    Over time, these weaknesses reduce financial control, slow decision-making, and impair an organization’s ability to manage travel spending consistently, accurately, and efficiently across global operations.

    What API-Issued Employee Cards Are

    API-issued employee cards are payment instruments provisioned through software interfaces as either virtual or physical cards for authorized staff use.

    Their defining feature is programmatic issuance and control, allowing organizations to set limits, merchant rules, and activation parameters with precision.

    Because card activity connects directly to finance systems, these cards also provide integrated access to spend data for oversight, reconciliation, and policy enforcement.

    Virtual And Physical Cards

    Within modern expense programs, virtual and physical cards function as company-controlled payment instruments issued to employees for approved business spending.

    Virtual formats support online purchasing and immediate provisioning, highlighting virtual card benefits and strong card issuance speed.

    Physical formats remain useful for travel, dining, and in-person vendor payments, while emphasizing physical card security through controlled use and identifiable ownership.

    Together, these options expand employee card flexibility across varied payment contexts without relying on personal funds or reimbursement delays.

    Their digital connection to finance platforms improves transaction tracking accuracy, strengthens expense management efficiency, and supports broader card integration capabilities with accounting and travel systems.

    The result is measurable user experience improvement for employees and finance teams, alongside clearer visibility into authorized business expenditures across departments, projects, and locations.

    Programmatic Issuance Controls

    As organizations expand the use of virtual and physical employee cards, attention often shifts from payment form factors to the control logic governing how those cards are created and used.

    API-issued card programs define issuance criteria in software, applying programmatic limits based on role, merchant category, geography, and duration. These control mechanisms enable automated approvals while preserving auditable user permissions and standardized compliance checks.

    They also support budgeting constraints by aligning card creation and spend thresholds with policy rules and departmental parameters. Continuous transaction monitoring can trigger real-time interventions, such as declines, alerts, or temporary suspensions, when activity falls outside approved conditions.

    Properly configured controls strengthen data security by minimizing unnecessary access and reducing manual handling. In aggregate, such controls improve operational consistency and contribute materially to enterprise risk management objectives overall.

    Integrated Spend Access

    Integrated spend access connects employee purchasing authority directly to enterprise systems through cards created, managed, and governed by application programming interfaces. This model embeds payment capability within procurement, travel, and expense workflows, allowing organizations to define limits, merchant rules, approval logic, and funding parameters in real time.

    Rather than relying on static card programs, companies can align card access with role, project, itinerary, or budget status. The result is tighter operational control and faster execution.

    API-issued cards support integrated budgeting by synchronizing spend permissions with policy engines and financial data sources. They also enable seamless transactions by reducing manual reimbursement steps, minimizing payment delays, and improving data capture at the point of purchase.

    Consequently, finance teams gain clearer visibility, stronger compliance, and more accurate allocation across departments, vendors, and activities.

    Expressing Controls at Card Creation

    The most powerful fraud control isn’t detection — it’s constraint. When every card carries programmatic rules for where, how often, and how much it can spend, entire fraud categories become impossible rather than merely detectable. Seeing how these rules are expressed in practice is easiest through a virtual card issuing API example that shows control parameters being set at card creation time.

    How Employee Cards Replace Reimbursements

    Although traditional reimbursement models have long governed business spending, employee cards replace that process by allowing authorized staff to pay approved travel and expense costs directly at the point of purchase. This shifts funding from the individual to the company, reducing out of pocket burden, reimbursement delays, and administrative friction.

    As employee reimbursement alternatives, API-issued employee cards connect transaction controls, merchant rules, and spending limits before payment occurs. Finance teams gain immediate visibility into travel, lodging, meals, and incidental expenses, while employees avoid preparing cash outlays for routine business activity.

    Receipt capture and policy mapping can occur alongside each transaction, supporting faster reconciliation and fewer reporting errors. The result is stronger corporate spend efficiency, improved compliance with approved budgets, and a more predictable expense workflow across distributed teams and operating environments globally.

    Why Shared Corporate Cards Create Risk

    Shared corporate cards often weaken spending accountability because multiple users can obscure who initiated specific transactions.

    This structure also increases exposure to fraud and misuse by reducing clear ownership and limiting effective oversight.

    As a result, organizations may face greater difficulty enforcing policy compliance and identifying irregular spending promptly.

    Weak Spending Accountability

    Expose a payment method to multiple employees, and accountability for each transaction becomes difficult to enforce. When several users access one corporate card, individual responsibility can blur, weakening accountability measures and reducing transaction transparency.

    Managers may struggle to align purchases with spending limits, approved purposes, or specific cost centers, which complicates budget tracking and diminishes reporting accuracy.

    Shared access also undermines employee awareness of expectations because card activity appears collective rather than personal. In that environment, policy adherence often depends on after-the-fact review instead of clear ownership at the point of purchase.

    Organizations then require stronger oversight strategies, more frequent reconciliation, and better documentation to preserve compliance standards. Without distinct card-to-employee assignment, financial literacy initiatives and controls become less effective in shaping disciplined spending behavior across teams.

    Fraud And Misuse Exposure

    Multiple employees using the same corporate card materially increase exposure to fraud and misuse because transaction authority becomes detached from clear individual identity. When purchases cannot be reliably tied to one cardholder, organizations face weaker audit trails, slower exception handling, and greater difficulty assigning responsibility for unauthorized, duplicate, or policy-violating spend.

    Shared credentials also undermine fraud prevention controls that depend on user-level monitoring, merchant pattern analysis, and timely escalation. Misuse detection becomes less effective because normal spending behavior cannot be established for a specific employee, reducing the value of alerts and post-transaction reviews.

    In practice, this ambiguity can conceal intentional abuse, accidental overreach, and card sharing beyond approved users. The result is higher operational risk, more disputed transactions, and increased investigation costs, especially during travel, reimbursement reconciliation, and internal compliance reviews across distributed teams.

    How API Cards Improve Spend Control

    Because spend limits and approval rules can be embedded directly into payment workflows, API cards give organizations more precise control over travel and expense activity. This structure supports spend efficiency by aligning authorizations with trip budgets, approved merchants, and real-time business needs.

    Centralized issuance and configurable logic strengthen budget adherence and financial accountability across distributed teams. Rich, immediate data improves transaction transparency, enabling finance functions to monitor usage patterns, reconcile charges quickly, and increase expense predictability.

    Approval automation reduces administrative delay while preserving compliance assurance through consistent, system-driven decisions. API connectivity also supports stronger vendor partnerships by linking booking, payment, and reporting processes.

    For employees, a streamlined user experience reduces out-of-pocket spending and reimbursement friction. At the same time, integrated data security measures help protect payment credentials and sensitive travel information.

    How Card Controls Enforce T&E Policy

    Building on the visibility and automation enabled by API cards, card controls apply those capabilities directly to travel and expense policy enforcement. Organizations can configure merchant category restrictions, geographic parameters, transaction timing rules, and approval conditions that align card usage with defined business purposes.

    These controls reduce reliance on post-expense review by preventing prohibited transactions before authorization. Policy execution becomes more consistent because controls operate automatically at the point of purchase.

    Companies can assign role-based permissions, trip-specific allowances, and spending limits that reflect employee level, destination, or budget. Temporary cards may be activated only for approved travel windows, while recurring exceptions can be encoded through system logic rather than manual oversight.

    The result is stronger card compliance, fewer policy breaches, and lower administrative effort in managing employee travel expenses overall.

    Real-Time Visibility Into Travel Spend

    How effectively can travel costs be managed when spending data is delayed until after a trip ends? API-issued employee cards address this limitation by enabling real-time tracking of transactions as they occur across airlines, hotels, meals, and ground transport.

    Immediate data capture strengthens budget oversight, supports expense forecasting, and improves spend analysis at both traveler and departmental levels.

    With transaction alerts, finance teams can identify anomalies quickly, maintain compliance monitoring, and respond to emerging cost patterns before they escalate.

    Effective data integration with accounting and enterprise resource planning systems increases financial transparency and reduces reconciliation lag.

    A centralized analytics dashboard consolidates merchant, category, and trip-level information, giving organizations a current view of liabilities and enabling more disciplined cost optimization throughout the travel lifecycle and decision making.

    Smarter Travel Expense Approval Flows

    When approval workflows are automated and policy driven, travel expense management becomes faster, more consistent, and easier to control at scale. Organizations benefit from automated approvals that route requests through a defined approval hierarchy, reducing delays and limiting subjective exceptions.

    Streamlined workflows support policy compliance by applying spending thresholds, category rules, and exception handling before costs escalate. This structure improves cost efficiency while preserving a reliable user experience for employees and finance teams.

    Enhanced visibility into pending, approved, and rejected items enables tighter oversight and faster intervention when anomalies appear. Data accuracy also improves because standardized validation rules reduce manual errors and incomplete submissions.

    Although integration challenges may affect implementation across existing travel and finance systems, well designed approval frameworks still strengthen governance, accelerate decisions, and improve operational consistency overall.

    How Employee Cards Sync Expense Data

    Employee cards can transmit transaction data directly into expense systems, enabling real-time expense matching with submitted records.

    This synchronization reduces manual reconciliation and improves the accuracy of reporting across travel and expense workflows.

    It also supports automated policy data sync, allowing controls and compliance rules to be applied consistently at the point of transaction.

    Real-Time Expense Matching

    Most modern travel and expense platforms support real-time expense matching by linking corporate card transactions directly to reporting systems as purchases occur. Transaction data, merchant details, timestamps, and amounts are transmitted through APIs, allowing expenses to appear almost immediately within employee dashboards. This reduces manual entry, accelerates review cycles, and improves record accuracy across distributed teams.

    Matched transactions can then be paired with receipts, itineraries, and project codes, enabling real-time reconciliation without waiting for monthly statement close. Systems also apply predefined rules for expense categorization based on merchant type, location, and spend patterns.

    Finance teams gain faster visibility into travel activity, while employees spend less time reconstructing purchases after trips. The result is a more current, verifiable expense record that supports efficient reporting, audit readiness, and stronger operational control overall.

    Automated Policy Data Sync

    Beyond real-time matching, automated policy data sync extends control by connecting employee card activity with the rules that govern allowable spend. API-issued cards can transmit automated data into expense platforms, where merchant category, location, limits, and approval paths are evaluated continuously for policy compliance. This improves expense accuracy by reducing manual coding and exception handling while increasing sync efficiency across finance systems.

    Well-structured integrations also strengthen data security through controlled permissions, audit trails, and standardized field mapping.

    Although integration challenges may arise with legacy tools, consistent schemas support reporting capabilities, better user experience, and system scalability as programs expand. By maintaining current policy logic across connected applications, organizations simplify compliance audits, reduce disputed reimbursements, and create a more reliable operating framework for corporate travel and expense oversight.

    When to Use Virtual vs Physical Cards

    When virtual or physical cards should be used depends on the nature of the expense, the level of control required, and the practical conditions of the transaction.

    Virtual card advantages are strongest in online bookings, one-time vendor payments, and situations requiring precise spending limits, rapid issuance, and detailed card management.

    Physical cards remain necessary where in-person acceptance, offline processing, or repeated merchant interaction affects user experience and transaction flexibility.

    However, physical card limitations include slower replacement, broader misuse exposure, and reduced merchant-level controls.

    Decisions should also weigh security concerns, especially for card-not-present transactions, alongside integration challenges within booking, expense, and accounting systems.

    A balanced program typically assigns virtual cards for controlled digital payments and physical cards for operational continuity where card-present transactions, mobility, or merchant infrastructure make tangible credentials more dependable.

    Employee Card Use Cases by Team

    Card format decisions become more effective when aligned with how different teams incur and manage spend. Sales personnel often require physical cards for travel, client meals, and incidental purchases made in person.

    Field operations may need durable cards for fuel, lodging, and equipment-related expenses across dispersed locations.

    Meanwhile, recruiting, marketing, and procurement teams frequently benefit from virtual cards for online bookings, software subscriptions, event fees, and vendor payments.

    Finance departments can assign controls based on team specific needs, including merchant restrictions, transaction limits, and expiration rules. This structure supports clearer budget allocation by linking card usage to departmental objectives and approved spending categories.

    As a result, employee cards function not only as payment tools, but also as operational instruments that reflect spending patterns, accountability requirements, and administrative efficiency across teams.

    What to Look for in a T&E Card API

    When evaluating a T&E card API, organizations typically prioritize features that strengthen control and streamline financial operations.

    Real-time spend controls help enforce policy at the point of transaction, reducing unauthorized or noncompliant expenses.

    Secure ERP integrations support accurate data transfer, faster reconciliation, and consistent reporting across travel and expense workflows.

    Real-Time Spend Controls

    Prioritize APIs that enable real-time spend controls at the point of authorization, not just after a transaction has posted. Effective platforms support dynamic controls based on merchant, geography, time, and amount, allowing organizations to enforce spending limits with precision.

    Granular user permissions further align card access with role, policy, and travel purpose.

    Strong real-time analytics improve budget tracking and compliance monitoring by surfacing exceptions immediately. Transaction alerts notify administrators and employees when attempted purchases violate policy or exceed thresholds.

    APIs should also classify expense categories automatically, strengthening fraud detection and reducing manual review. Robust data reporting completes the control framework by providing timely visibility into approvals, declines, and policy breaches.

    Together, these capabilities make API-issued employee cards more governable, responsive, and operationally efficient for modern travel programs.

    Secure ERP Integrations

    Evaluate ERP integration capabilities through a security and data-governance lens, because T&E card APIs routinely transmit sensitive financial, employee, and approval data into core accounting systems.

    Selection criteria should include encryption in transit and at rest, tokenization, role-based access controls, audit logging, and support for least-privilege authentication frameworks such as OAuth and SAML.

    Organizations should also verify ERP compatibility across major platforms, including support for custom fields, approval hierarchies, tax codes, and multi-entity accounting structures.

    Robust APIs should provide webhook integrity checks, idempotent transaction handling, error visibility, and reconciliation-ready data mappings.

    Vendors offering secure payment solutions should document data residency, retention policies, incident response procedures, and third-party security certifications.

    The objective is not merely connectivity, but controlled, accurate, and compliant financial data exchange at scale.

    How to Roll Out Employee Cards

    Rolling out employee cards requires a controlled implementation plan that aligns card access, spending rules, and approval workflows with organizational policy.

    Implementation typically begins with eligibility criteria, role-based limits, merchant controls, and documented exception handling. Finance, procurement, and security teams should define ownership across issuance, policy enforcement, reconciliation, and card management.

    A phased deployment reduces operational risk. Organizations often begin with a pilot group, validate system integrations, and refine approval paths before broader release.

    Employee onboarding should include policy acknowledgement, permitted use cases, receipt requirements, and escalation procedures for declined transactions or suspected misuse. API-based provisioning can support instant issuance, temporary limits, and automatic deactivation when employment status changes.

    Ongoing administration should include periodic policy reviews, audit sampling, support procedures, and standardized training for managers and cardholders across departments.

    How to Measure Employee Card ROI

    Measure employee card ROI by comparing total program costs with quantifiable operational and financial gains over a defined period. Relevant ROI metrics include implementation fees, interchange effects, administrative labor, fraud losses, and working capital changes.

    Cost analysis should isolate baseline travel and expense processes, then measure post-launch differences in reimbursement speed, exception handling, and reconciliation effort.

    Evaluation should also track efficiency gains from automation, policy enforcement, and real-time controls. Compliance impact can be assessed through reduced out-of-policy spend, fewer audit findings, and stronger documentation quality.

    Spend trends and usage patterns reveal adoption levels, merchant concentration, and category leakage. Budget forecasts improve when card data increases visibility into recurring travel and expense obligations.

    Employee satisfaction matters because better user experience can reduce support tickets, reimbursement delays, and unofficial spending workarounds significantly.

    Frequently Asked Questions

    Are Api-Issued Employee Cards Accepted Internationally Without Foreign Transaction Issues?

    Yes, API-issued employee cards are generally designed for international acceptance, depending on network coverage and issuer policies. Foreign transactions usually work without unusual issues, although fees, compliance checks, currency conversion terms, and regional merchant restrictions may apply.

    How Are Disputed Charges Handled on Employee-Issued Corporate Cards?

    Disputed charges on employee-issued corporate cards are typically handled through structured dispute resolution processes, beginning with charge verification, merchant inquiry, and supporting documentation review. Issuers may provisionally credit accounts while investigations proceed under applicable network rules.

    Can Employee Cards Support per Diem Allowances for Travel?

    Yes, employee cards can support per diem allowances for travel through configurable spending limits, automated per diem calculations, and merchant controls, helping organizations enforce travel policy compliance while reducing manual reimbursement processes and improving oversight of employee expenses.

    What Happens to Employee Cards When Someone Leaves the Company?

    Upon an employee’s departure, cards are typically gracefully retired through a card deactivation process, preventing further use. Any outstanding charges are handled under employee reimbursement policies, ensuring orderly closure, financial control, and administrative continuity.

    Are Api-Issued Employee Cards Compatible With Travel Booking Platforms?

    Yes, API-issued employee cards are generally compatible with many travel booking platforms through travel booking integration, provided issuer support and merchant acceptance align. Compatibility also depends on controls, tokenization, and employee card security requirements across booking workflows.

    Final words

    API-issued employee cards present a practical path to more disciplined, data-driven travel and expense management. By replacing paper-heavy reimbursements and reducing reliance on shared cards, they support stronger controls, clearer compliance, and faster financial workflows. With careful rollout, measurable policies, and reliable API infrastructure, organizations can create a smoother, safer spend environment. The result is streamlined spending, simplified supervision, and more consistent corporate control across teams, trips, and transactions.
  • Virtual Cards for Online Marketplaces and Resellers in Greece

    Virtual Cards for Online Marketplaces and Resellers in Greece

    You’ll cut fraud, speed vendor onboarding, and tighten spend control by issuing tokenized virtual cards with programmable limits, dynamic CVV, and short lifespans. They automate payouts, reduce reconciliation time, and can lower unauthorized purchases by up to 40%, improving cash flow visibility and dispute resolution. In Greece, virtual cards help marketplaces manage e‑commerce growth while meeting AML/KYC, VAT, and transaction reporting needs. Keep going to see provider selection, integration steps, and compliance tips.

    Key Takeaways

    • Virtual cards reduce fraud and unauthorized spend for Greek marketplaces and resellers through tokenization, dynamic CVV, and short-lived card numbers.
    • They streamline vendor payments and onboarding with instant issuance, automated payouts, and transaction-level reconciliation.
    • Implement granular controls (per-transaction, daily, merchant-specific limits) and automated expirations to limit long-term exposure.
    • Compliance requires partnering with licensed payment institutions to address AML/KYC, VAT reporting, and transaction-level submission obligations.
    • Pilot integrations, transparent pricing, and SLA-driven KPIs ensure measurable ROI and operational reliability before full rollout.

    Who Should Use Virtual Cards?

    Who should use virtual cards? You should, if you run an online marketplace or resell across Greece and prioritize scalable controls, better user experience, and measurable cost savings.

    You’ll deploy virtual cards to isolate vendor payments, reduce fraud exposure, and cut reconciliation time—data shows automated payouts lower manual processing costs significantly. Platforms managing high transaction volumes will see ROI faster; smaller sellers benefit when you limit card lifespans to specific orders, reducing chargeback rates.

    Use them if you need granular spend policies, easy integration with APIs, and clear audit trails for compliance.

    Don’t expect them to replace core banking overnight, but do expect improved cash flow visibility, faster dispute resolution, and predictable reductions in operational expenses.

    How Virtual Cards Actually Work : Numbers, Limits, Lifecycle

    You’ll see virtual cards use the same numbering conventions as physical cards—PAN-like numbers, expiry, and CVV—but formats can be tokenized or gateway-specific for security and reconciliation.

    Settable limits (per-transaction, daily, merchant-specific) and automatic expiration control fraud and cash flow, so choose policies that match your marketplace risk and spend patterns.

    Understanding issuance-to-expiry lifecycle—from one-time single-use to multi-month virtual cards—lets you optimize vendor onboarding, refunds, and auditing.

    Numbering And Formats

    Card numbers on virtual cards follow the same ISO and industry standards as physical cards (ISO/IEC 7812), but issuers use dynamic schemes, tokenization, and shorter lifecycles to control risk and track usage.

    You’ll see a mix of numbering formats: static PANs that mirror plastic cards, single-use PANs generated per transaction, and tokenized identifiers presented to merchants while the real PAN is stored securely.

    Different card types—debit, credit, prepaid, and commercial—use distinct BIN ranges and metadata to route authorizations and apply rules.

    For marketplaces and resellers in Greece, that means you can programmatically request the appropriate numbering format based on supplier risk, reconciliation needs, and settlement flows.

    Use analytics on BIN and token patterns to detect anomalies and optimize routing.

    Limits And Lifecycle

    Although virtual numbers can mirror plastic PANs, their lifecycle and limits are where issuers enforce control, and you’ll see this expressed through expiry windows, spend caps, and usage rules tied to tokens or BINs.

    You’ll set lifecycle management policies that define issuance-to-expiry timelines, single-use versus multi-use modes, and automated rotation to reduce fraud.

    Transaction limitations are quantifiable: per-transaction ceilings, daily/monthly spend caps, and merchant-category blocks that enforce usage constraints.

    Virtual card security comes from tokenization, dynamic CVV, and cryptographic binders to devices or sessions.

    Feature enhancements often add real-time analytics, instant lock/unlock, and programmable rules for marketplaces and resellers.

    Ensure all settings map to compliance requirements—KYC thresholds, AML monitoring, and audit trails—to balance operational agility with regulatory safety.

    How One Agency Sorted Out Client Billing

    Agencies pay for dozens of tools on clients’ behalf, and it gets confusing fast. An agency owner we know assigns each client a virtual Mastercard so billing maps neatly to projects. She recommended Card29, and it sorted our own client accounting overnight. Every client’s tools sit on a dedicated prepaid card, capped and labeled, so passing costs through stays transparent and exact. For service businesses lost in shared-credit-card confusion, that VCC structure brings instant clarity.

    Why Greece’s Marketplaces Need Virtual Cards Now

    Because Greece’s e-commerce sector is scaling fast while fraud and payment fragmentation are rising, marketplaces need virtual cards now to cut risk, control spend, and streamline cross-border payouts.

    You’ll benefit from measurable gains: virtual cards reduce fraud surface, support reconciliation, and align with digital payment trends that buyers and partners expect. By issuing single-use or merchant-scoped cards, you limit exposure and automate accounting, improving marketplace efficiency and cash flow forecasting.

    Regulators and banking partners are also pushing for clearer AML controls, making tokenized payments a competitive advantage. Implementing virtual cards helps you respond to market signals quickly, lower dispute resolution costs, and scale vendor payments without adding headcount.

    • Protect revenue and reputation
    • Reclaim time with automated controls
    • Scale confidently across borders

    Top Use Cases for Sellers and Platforms (Examples & ROI)

    You’ll see clear ROI when you use virtual cards to enforce expense controls and set per-transaction or time-bound limits, reducing overspend and reconciliation time by up to 30–40%.

    Instant virtual issuance lets you provision cards for sellers, contractors, or marketing campaigns in seconds, cutting payment friction and accelerating vendor onboarding.

    Next, we’ll quantify savings and show real examples of limit-configured cards in marketplace workflows.

    Expense Control & Limits

    When marketplaces and sellers implement virtual cards with built-in spend controls, they cut unauthorized and off-policy purchases by up to 40% while tightening reconciliation and forecasting. You gain real-time expense tracking and tighter budget management that reduce month-end surprises and manual audits.

    You set per-card limits, merchant controls, and expiry windows so teams spend only where policy allows, improving ROI through fewer chargebacks and faster bookkeeping. Data-driven alerts and exportable reports let you spot anomalies and reallocate funds quickly, boosting cash efficiency.

    • Feel secure knowing every euro has a rule and a record.
    • Feel empowered as teams spend within clear, enforced boundaries.
    • Feel confident when forecasts match actuals and margins improve.

    Instant Virtual Issuance

    If you need on-demand payment credentials, instant virtual issuance turns cash flow into action: platforms and sellers can generate single-use or limited-life cards in seconds for payouts, supplier payments, trial subscriptions, or one-off refunds, cutting payment friction and fraud while improving reconciliation.

    You’ll reduce capital lock-up and lower chargeback risk by issuing cards tied to specific orders, time windows, or budgets. In resale models, instant issuance speeds supplier onboarding and automates drop-ship payments; marketplaces report 30–50% fewer disputes and 20% faster settlement when paired with tokenized digital wallets.

    Measure ROI through reduced fraud loss, fewer manual refunds, and staff-hours saved on reconciliations. Prioritize API reliability, real-time reporting, and tokenization to maximize uptime and compliance in Greece’s PSD2 environment.

    Virtual Cards for Onboarding and Reconciliation

    Because onboarding speed and clean reconciliation directly impact marketplace margins, virtual cards let you automate supplier activation and tie every payment to a single, auditable transaction.

    You’ll accelerate onboarding strategies by issuing cards instantly, reducing time-to-first-sale and lowering drop-off rates. With embedded metadata per card, you’ll resolve reconciliation challenges faster: each charge maps to orders, commissions, and VAT entries, cutting manual matching by up to 80%.

    Real-time feeds feed accounting systems, so your finance team closes books sooner and detects anomalies immediately.

    • Relief when audits require immutable trails.
    • Confidence that payouts match contracts without guesswork.
    • Pride in running a lean, data-driven marketplace.

    Adopt measurable KPIs—activation time, mismatch rate, reconciliation cycle—to prove ROI.

    Controlling Spend: Rules, Expiry, and Merchant Blocks

    While you scale supplier networks, controlling spend with granular rules, expirations, and merchant blocks keeps costs predictable and fraud low.

    You set spending limits per vendor and per card to enforce budget management, tying transaction categories to automated approvals so purchases match policy.

    Use merchant authorization and merchant blocks to prevent off‑policy suppliers, and apply expirations to limit long‑term exposure.

    Grant user permissions narrowly, logging actions for compliance tracking and enabling real‑time reporting tools that surface anomalies.

    Integrate expense auditing workflows to reconcile virtual card activity with invoices and P&L categories.

    This approach reduces manual review time, supports data-driven decisions, and complements broader card security and fraud prevention strategies without sacrificing operational agility.

    Fraud Reduction: Security Features to Prioritize for Virtual Cards

    You should prioritize tokenized card numbers to eliminate static PAN exposure and reduce breach impact.

    Combine that with dynamic spending controls—per-transaction limits, merchant/category restrictions, and short lifespans—to cut fraud windows by design.

    Tie both to real-time transaction monitoring so you can flag anomalies and stop suspicious flows within seconds.

    Tokenized Card Numbers

    When marketplaces adopt tokenized card numbers, they replace real PANs with unique tokens that limit exposure and stop reuse across merchants. You’ll see tokenization benefits in secure transactions and privacy protection, with tokens stored instead of PANs to reduce breach impact.

    This supports fraud prevention and improves transaction tracking for dispute resolution. Integrate tokens with digital wallets to preserve user experience and ease of use while enabling spending flexibility and better financial management.

    Metrics show lower chargeback rates and faster reconciliation when tokenization’s applied consistently. You should require token lifecycle policies, strict key management, and vendor SLAs to maximize resilience.

    Tokenization complements but doesn’t replace other controls, so include it as a core layer in your security stack.

    • Relief: reduced breach risk feels empowering
    • Trust: customers gain confidence quickly
    • Control: you manage payments with clarity

    Dynamic Spending Controls

    Because virtual cards let you issue credentials in real time, you should pair them with dynamic spending controls that enforce rules at the card level—limits by amount, merchant category, geo, time window, and single-use or multi-use lifetimes—to block unauthorized charges before they occur.

    You’ll reduce fraud exposure by applying adaptive spending policies that adjust limits based on risk signals: vendor reputation, transaction velocity, and historical patterns.

    Implement dynamic budgeting strategies so each card ties to a specific budget line, expiration, and reconciliation tag, cutting lateral movement and overspend.

    Track control efficacy with conversion and decline-rate metrics, iterating rules where false positives impact merchants.

    Prioritize controls that are automated, auditable, and reversible to balance security with merchant experience.

    Real-Time Transaction Monitoring

    Pairing dynamic spending controls with real-time transaction monitoring gives you both preventive and detective layers: controls block likely bad charges, while real-time monitoring catches anomalous behavior that rules miss.

    You’ll rely on transaction analytics to spot patterns in consumer behavior and market trends, feeding fraud detection models that adapt instantly.

    Tight integration with platform integration and budgeting strategies keeps user experience smooth while enforcing limits.

    Track performance metrics to measure false positives, resolution time, and compliance issues to stay audit-ready.

    Prioritize data security across feeds and raw logs so analysts can act without risking exposure.

    • You’ll feel safer knowing threats are caught fast.
    • You’ll regain control of company spend and stress.
    • You’ll trust decisions backed by measurable data.

    Regulation, Tax & Reporting for Virtual Cards in Greece

    Although Greece’s financial regulators and tax authorities haven’t issued a single exhaustive rulebook for virtual cards, you still must navigate a clear set of obligations covering licensing, AML/KYC, VAT treatment, and transaction reporting that affect both marketplace operators and card issuers.

    You need to prioritise regulatory compliance across legal frameworks and manage compliance challenges proactively: licensing or partnering with authorised payment institutions, implementing AML/KYC, and maintaining audit-ready transaction logs.

    Assess tax implications and tax obligations for commission, VAT on services, and cross-border flows; document taxable events and apply reverse-charges where relevant.

    Design reporting processes to meet domestic and EU requirements, support financial transparency, and automate submission of transaction-level data.

    Use measurable controls, periodic reviews, and reconciliations to reduce risk and regulator scrutiny.

    Choosing a Provider: Integrations, Pricing, and SLAs

    When selecting a virtual-card provider, focus first on integration compatibility, predictable pricing, and enforceable SLAs so you can measure operational impact and cost per transaction from day one.

    You’ll evaluate integration challenges against your stack, quantify expected downtime in service level agreements, and compare provider comparisons with scenario-based cost models.

    Use pricing strategies that separate fixed fees, per-card costs, and contingency charges so unit economics stay transparent.

    Demand SLAs with measurable KPIs, penalties, and escalation paths.

    Build a short RFP template that stresses API specs, error rates, and settlement windows to avoid surprises.

    Make decisions driven by sample data, not promises, and prioritize providers that report historical uptime and real incident metrics.

    • Relief when an SLA actually protects your margins
    • Confidence from clear pricing
    • Frustration avoided through honest integration testing

    Implementation Roadmap: Pilot to Full Rollout

    Before you scale, run a tightly scoped pilot that validates integration, reconciliation, and fraud controls against real transaction volumes so you can quantify error rates, latency, and cost-per-transaction.

    Design a pilot program with clear success metrics informed by market analysis and compliance guidelines.

    Map technology requirements, data flows, and a scalability strategy that anticipates peak loads.

    Conduct a formal feedback session with merchants, resellers, and internal teams to capture user experience issues and operational gaps.

    Perform a risk assessment that prioritizes fixes by impact and probability.

    Allocate training resources and stakeholder engagement plans so operations and support are ready.

    After measured KPI attainment, phase rollout geographically and by segment, monitoring costs, SLA adherence, and regulatory controls for continuous improvement.

    Marketplace-Specific Integration Failures and Fixes

    Because marketplaces stitch together multiple systems and third-party providers, integration failures usually reveal themselves as predictable gaps—API mismatches, auth/token expirations, webhook loss, and reconciliation drift—that drive lost transactions and support churn.

    You’ll face integration challenges and compatibility issues that degrade user experience and expose software limitations; map touchpoints, log metrics, and quantify failure rates.

    Use troubleshooting strategies like automated retry logic, token refresh workflows, synthetic monitoring, and end-to-end reconciliation to close gaps. Demand clear vendor support SLAs and run compatibility tests before rollout.

    Prioritize fixes by impact: payment failures first, then settlement drift, then UX glitches. Measure post-fix improvements and iterate.

    • You’ll feel the pressure when transactions fail.
    • You’ll lose trust if issues persist.
    • You’ll win back confidence with reliable fixes.

    Final words

    You’ve spent time building a marketplace, so of course you’ll ignore virtual cards—until SKUs vanish, refunds balloon, and reconciliation feels like witchcraft. Ironically, the very tool that slices fraud, automates payouts, and gives you line-item spend data is also the one you’ll procrastinate on integrating. Don’t. Run a brief pilot, measure reductions in chargebacks and reconciliation hours, then scale. Data-driven fixes beat heroic fire-fighting every single time.

  • Can You Use a Virtual Credit Card on Amazon in Canada?

    Can You Use a Virtual Credit Card on Amazon in Canada?

    Yes — you can use a virtual credit card on Amazon.ca for most purchases by entering the card number, expiry and CVV and matching the billing name and address. Temporary authorization holds or AVS mismatches can cause declines, so check limits, expiry and issuer rules for recurring charges. Single‑use or low‑limit numbers may fail for subscriptions. If you want reliable tips on setup, troubleshooting and safer alternatives, keep going for clear, practical steps and examples.

    Can You Use a Virtual Credit Card on Amazon.ca?

    Can you use a virtual credit card on Amazon.ca? Yes—you can often add a virtual card as a payment method if it supplies a valid card number, expiry date, and CVV.

    You’ll enter those details where you’d normally add a new credit card, and Amazon treats it like any other card for purchases and subscriptions.

    Using a virtual card benefits you by limiting exposure: you can set single-use numbers or short expiry dates to reduce fraud risk. That enhances online shopping security because stolen numbers quickly become useless.

    Still, verify your card issuer supports recurring payments if you plan subscriptions, since some virtual cards are single-use and may disrupt automatic billing.

    Check issuer terms before relying on one for ongoing charges.

    Quick Test: Add a Virtual Card to Amazon in 3 Steps

    Before you commit, run a quick test by adding your virtual card to Amazon’s payment methods so you can confirm it works for purchases and recurring charges.

    Step 1: generate or select a virtual card from your bank or card app and copy the card details.

    Step 2: sign into your Amazon account, go to Your Payments, choose Add a credit or debit card, and paste the virtual card information.

    Step 3: set the virtual card as default for a small test purchase or a low-cost subscription, then monitor the charge.

    This quick check lets you verify compatibility, enjoy virtual card benefits like controlled spending and reduced exposure, and continue Amazon shopping confidently if the charge processes successfully.

    How Virtual Credit Cards Work (Number, CVV, Expiry)

    When you get a virtual credit card, it comes with its own card number, CVV, and expiry just like a physical card.

    You’ll enter those details at checkout on Amazon in Canada the same way you’d with a regular card.

    Below we’ll explain how temporary numbers, changing CVVs, and short expirations affect one-time and recurring purchases.

    Virtual Card Number

    A virtual card number is a temporary, system-generated substitute for your real card details that you can use for online purchases; it includes its own number, CVV, and expiration so merchants never see your actual account information.

    You’ll get a unique number tied to your account that isolates each merchant interaction, improving card security and reducing exposure if a site is breached. Issuers let you set transaction limits or single-use flags, so you control how much can be charged.

    • You can create numbers instantly for specific merchants or one-off purchases.
    • Numbers are linked to your real account but block direct access to it.
    • You can set transaction limits to cap spending per virtual card.
    • You can cancel or expire a number without affecting the main card.

    CVV And Expiry

    Because virtual cards are meant to stand in for your real card, they also come with their own CVV and expiration date that merchants see instead of your primary account details.

    When you use a virtual card on Amazon, you’ll enter that card’s CVV and expiry dates at checkout just like with a physical card.

    Issuers generate a unique CVV to provide CVV security separate from your main account, so even if a merchant stores those digits, your real card info stays hidden.

    Expiry dates can be short-lived or match the virtual card’s lifespan; some providers let you set a single-use or limited-time expiry to reduce fraud risk.

    Always check the virtual card’s expiry before placing recurring orders.

    The Envelope Method, Reinvented for Online Spending

    Budgets are far easier to keep when the cash simply runs out. A money-smart friend treats her virtual debit card alternative for everyday budgeting like a cash envelope—fixed amount in, and that’s the limit. She pointed us to Qwikvcc, and it’s quietly become a budgeting favorite. Rather than leaning on willpower against an open credit card, we set the cap when loading the prepaid card and let it police us. It’s the old envelope system, finally dragged into the digital age.

    Amazon.ca Verification & Billing Rules for Virtual Cards

    Although virtual credit cards simplify online payments, Amazon.ca still enforces specific verification and billing rules you’ll need to follow: you must provide matching name and billing address, verify small authorization charges, and respect your card issuer’s virtual card security settings and transaction limits.

    Amazon may decline mismatched details or one-time-use numbers that expire before settlement.

    • Ensure the billing name/address on Amazon matches the virtual card profile.
    • Expect temporary authorization holds; confirm amounts in your card portal.
    • Use cards with sufficient transaction limits and valid expiry for order processing.
    • Be ready to complete identity checks if Amazon flags the payment.

    Follow these rules to reduce declines and speed order fulfillment while preserving your virtual card security.

    How to Set Billing and Shipping for a Virtual Card on Amazon

    When you add a virtual card to your Amazon.ca account, set the card’s billing address to match the one your issuer has on file so the verification checks pass.

    If you’re shipping to a different location, add that address as a separate shipping address in your account and select it at checkout.

    Don’t forget to pick the correct billing address on the payment page to avoid payment errors.

    Set Billing Address

    Start by adding the virtual card as a payment method in your Amazon account, then confirm its billing address matches what the card issuer has on file; if the two don’t match, payments will likely be declined.

    You’ll want to complete billing address verification before checkout to avoid failed charges. Use address formatting tips from your issuer—abbreviations, unit numbers, and postal code formatting matter. Update Amazon’s payment settings to mirror the issuer’s record exactly.

    • Check full name, street, unit/suite, city and province for exact matches.
    • Enter the postal code precisely, including spacing and capitalization if specified.
    • Avoid extra punctuation or nonstandard abbreviations that might trigger verification errors.
    • Save and re-select the card at checkout to confirm the verified billing address is active.

    Match Shipping Address

    After you’ve matched the billing address to the virtual card issuer’s record, make sure the shipping address aligns with that billing information or with an authorized address on the card.

    On Amazon, you’ll add or select a shipping address during checkout; choose one that passes address verification to avoid declines. Some virtual cards impose shipping restrictions—like limiting delivery to your verified home or a cardholder’s confirmed alternate—so confirm permitted addresses with the issuer before ordering.

    If Amazon flags the address, update it to match formatting the issuer uses (unit numbers, postal code). For gift purchases, consider using an alternate recipient’s address only if the card issuer explicitly authorizes it.

    Double-check both billing and shipping to smooth approval and delivery.

    Common Problems Adding Virtual Cards : And Fast Fixes

    Although virtual cards make online payments simpler, you’ll still run into a few common hiccups when adding them to Amazon Canada—expired or mismatched billing info, issuer restrictions on merchant types, and temporary AVS or verification failures are the usual culprits.

    You’ll want to confirm billing address, expiration, and CVV right away, and check issuer rules about merchant categories and transaction limits. For security, enable virtual card security features and whitelist Amazon if your issuer offers it.

    If a charge is declined, try a quick reissue or use the physical card as a backup.

    • Verify billing address and CVV match your Amazon account
    • Check issuer merchant restrictions and transaction limits
    • Reissue the virtual card or refresh details in your wallet
    • Contact issuer support for AVS or verification errors

    Canadian Virtual Card Issuers That Work With Amazon.Ca

    When you’re shopping on Amazon.ca, several Canadian issuers and fintechs provide virtual card options that are compatible with the site—each with different rules on merchant acceptance, funding sources, and security features.

    You’ll find popular options from banks and apps that highlight virtual benefits like single-use numbers, instant issuance, and spending controls.

    Check Canadian issuers for integration with digital wallets and whether they present a standard card number, expiry, and CVV Amazon accepts.

    Read User experiences to confirm success with checkout and customer support responsiveness.

    Evaluate Security features such as tokenization, transaction alerts, and lock/unlock controls.

    Be aware of Card limitations—some virtual cards block certain merchant categories, limit amounts, or don’t support address verification—so confirm terms before relying on them.

    Why Virtual Cards Fail for Subscriptions and Recurring Payments

    Because virtual cards often generate single-use numbers or let you set strict limits, they can break recurring charges that expect a stable card on file. You’ll find subscription management systems and merchants often fail to accept rotating numbers, declined renewals trigger service interruptions, and automated retries can’t fix an expired token. That means you’ll need to monitor every renewal closely.

    • Single-use or short-lived numbers cause immediate declines on recurring billing attempts.
    • Spending caps or merchant restrictions block subsequent automatic charges.
    • Tokenization mismatch: some platforms won’t update to a new virtual number automatically.
    • Notifications may be missed, so you won’t catch failed payments before service lapses.

    Plan around these limits when you rely on subscriptions.

    Alternatives If a Virtual Card Won’t Work (Gift Cards, Prepaid, Wallets)

    If a virtual card doesn’t work on Amazon, you can load your account with an Amazon Gift Card and pay directly from your balance.

    You can also use reloadable prepaid cards that behave like debit/credit and are often accepted at checkout.

    Finally, check digital wallets linked to your account — they can provide a seamless alternative if the virtual card is rejected.

    Amazon Gift Card Use

    Although a virtual credit card sometimes won’t work on Amazon Canada, you’ve got solid alternatives: Amazon gift cards, prepaid cards, and digital wallets can keep you shopping without a linked physical card.

    Gift card benefits include immediate balance use, easy gifting, and bypassing card verification hiccups. You’ll follow a simple redemption process: enter the code at checkout or in Your Account to apply funds to your balance. Use gift cards for Prime subscriptions, third-party sellers, and most digital content.

    • Buy Amazon gift cards online or at retail stores for quick funding.
    • Combine multiple gift cards to cover larger purchases.
    • Check expiration and regional restrictions before buying.
    • Keep codes secure; treat them like cash.

    Reloadable Prepaid Cards

    When a virtual credit card won’t pass Amazon Canada’s verification, reloadable prepaid cards give you a reliable, card-like payment option without needing a bank account or long-term credit line.

    You can buy a reloadable prepaid card from banks, retailers, or online issuers, load funds, and use the card’s number on Amazon like a regular debit or credit card.

    Check reloadable limits before you buy — some cards cap monthly reloads or maximum balances, which affects large purchases.

    These cards offer spending flexibility: you control how much is loaded and avoid overdrafts or credit checks.

    Keep receipts and register the card if possible to recover funds if it’s lost, and verify Amazon accepts the issuer before relying on it.

    Digital Wallet Payments

    Looking for alternatives when a virtual card won’t clear Amazon Canada’s checks? You can use digital wallets like Apple Pay or Google Pay where accepted, or rely on Amazon gift cards and reloadable prepaid cards to complete purchases.

    Digital wallets enhance payment security by tokenizing card details and often require biometrics, reducing fraud risk. If Amazon rejects a virtual card, try these options:

    • Buy Amazon gift cards with a bank transfer or at a store, then redeem on your account.
    • Use a reloadable prepaid card issued to your name to satisfy billing match rules.
    • Pay via compatible digital wallets on supported devices for faster checkout and added payment security.
    • Link a conventional credit card as a fallback for recurring or larger purchases.

    Safety Tips & Best Practices When Using Virtual Cards on Amazon

    Because virtual cards limit exposure of your real account details, you should still follow a few key precautions to keep purchases safe on Amazon Canada.

    Use virtual card security best practices: set single-use or merchant-locked numbers, cap spending limits, and expire numbers promptly after purchase.

    Link only to trusted Amazon accounts and avoid saving virtual details in public or shared profiles.

    Monitor transactions frequently and enable alerts for any charge attempts.

    Keep your device and Amazon app updated, use strong passwords with two-factor authentication, and avoid public Wi‑Fi when completing payments.

    If a charge looks suspicious, contact your card issuer immediately to freeze or cancel the virtual number and dispute the transaction to minimize risk.

    Frequently Asked Questions

    Can Virtual Cards Be Used for Amazon Prime Student or Other Discounts?

    Yes — you can often use virtual cards for Amazon Prime Student and other student discounts, but you’ll want to confirm virtual card benefits like billing address match, recurring-authorize support, and issuer policies to avoid unexpected declines.

    Will Amazon.Ca Store My Virtual Card Details for Later Use?

    About 60% of shoppers reuse saved cards, and you won’t always be among them: Amazon.ca can store your virtual card for future purchases, but virtual card security and transaction limitations may prevent saving or recurring use.

    Can I Use a Virtual Card With Amazon Pay on Other Websites?

    Yes — you can use a virtual card with Amazon Pay on other websites if the merchant accepts the virtual card’s network; you’ll benefit from virtual card security while payment processing follows the merchant’s gateway and Amazon Pay rules.

    Do Virtual Cards Work for Amazon Marketplace Sellers Outside Canada?

    Yes — but consider flags: a virtual card’s limitations can block some international seller options, so you’ll need cards that allow cross-border billing, match address requirements, and accept merchant verification to ensure successful Amazon marketplace purchases.

    Can I Add a Virtual Card to an Amazon Household Account?

    Yes — you can add a virtual card to an Amazon Household account if the card’s issuer allows online merchant billing; you’ll manage it via household account settings, enjoying virtual card security while sharing payment methods with family members.

    Final words

    Think of a virtual card as a short-lived spark: great for one-off Amazon.ca buys but fizzling with recurring charges. You can usually add the card’s number, CVV, and expiry like a physical card, match billing and shipping addresses, and shop safely—yet subscriptions, some verification checks, or merchant holds can snuff it out. If it fails, pivot to gift cards, prepaid cards, or a wallet. Use strong passwords, monitor statements, and keep that spark controlled.

  • Top Online Payment Methods in Bangladesh for Secure Digital Transactions

    Top Online Payment Methods in Bangladesh for Secure Digital Transactions

    Introduction

    Digital payments have become a major part of business and personal transactions in Bangladesh. The growth of e-commerce, online services, digital subscriptions, and mobile banking has increased the demand for secure and reliable payment methods. Consumers expect fast and convenient transactions, while businesses need systems that ensure security, efficiency, and smooth payment processing.

    online payment methods in Bangladesh help individuals and organizations transfer funds electronically without relying on cash transactions. These solutions simplify financial operations, improve transaction speed, and support the growth of the digital economy.

    Just as Industrial infrastructure services in Western Australia provide essential support for industrial projects and operations, online payment systems provide the digital infrastructure needed to support secure financial transactions across multiple industries.

    What Are Online Payment Methods?

    Online payment methods are digital solutions that allow users to send, receive, and process payments electronically through websites, mobile applications, and online platforms.

    These systems connect customers, merchants, banks, and payment processors through secure networks. The payment process involves transaction verification, authorization, and fund transfer within a short period of time.

    Modern payment methods help businesses improve customer experiences while reducing the complexity associated with traditional payment processes.

    Why Online Payment Methods Matter

    Businesses and consumers increasingly depend on digital transactions for convenience and efficiency.

    Online payment methods offer faster transaction processing, improved security, and greater accessibility compared to traditional payment systems.

    They also support round-the-clock transactions, allowing payments to be completed at any time regardless of business hours.

    As digital commerce continues to expand, secure payment methods play a crucial role in supporting economic growth and business development.

    Popular Online Payment Methods in Bangladesh

    Payment Gateways

    Payment gateways are among the most widely used solutions for online businesses.

    These platforms securely process transactions and support multiple payment channels, including cards, mobile financial services, and internet banking.

    Payment gateways help businesses manage transactions efficiently while maintaining strong security standards.

    Debit and Credit Card Payments

    Debit and credit cards remain common payment methods for online purchases.

    Customers can make secure payments through websites and mobile applications using card-based transactions.

    Many payment systems support both local and international card networks.

    Mobile Financial Services

    Mobile financial services have transformed digital payments in Bangladesh.

    These services allow users to transfer money, pay bills, purchase products, and complete transactions directly through mobile devices.

    Their convenience and accessibility have contributed to widespread adoption across the country.

    Internet Banking

    Internet banking enables customers to make payments directly from their bank accounts through secure online banking portals.

    This payment method is often used for business transactions, utility payments, and online purchases.

    Digital Wallets

    Digital wallets store payment information electronically and allow users to make transactions without repeatedly entering financial details.

    These solutions simplify the payment process and improve user convenience.

    QR Code Payments

    QR code payments allow customers to scan a code and complete transactions using a mobile device.

    This method has gained popularity due to its speed, simplicity, and contactless nature.

    Security Features of Online Payment Methods

    Security is a critical factor in digital payment systems.

    Encryption Technology

    Encryption protects financial information while it is transmitted between users and payment providers.

    This technology helps prevent unauthorized access to sensitive data.

    Tokenization

    Tokenization replaces payment information with unique digital identifiers.

    This process reduces the risk of exposing financial details during transactions.

    Fraud Detection Systems

    Advanced fraud monitoring tools analyze transaction behavior and identify suspicious activities in real time.

    These systems help reduce financial losses and improve transaction security.

    Multi-Factor Authentication

    Multi-factor authentication requires additional identity verification before payments are authorized.

    This extra security layer helps protect customer accounts and payment information.

    The focus on secure operations is similar to Industrial infrastructure services in Western Australia, where reliability and risk management are essential for maintaining operational performance.

    Benefits of Online Payment Methods

    Online payment systems provide several important advantages.

    They improve transaction speed and reduce payment delays.

    They enhance customer convenience by offering multiple payment options.

    They support secure transactions through advanced security technologies.

    They reduce administrative workload through automation.

    They provide detailed transaction records that help businesses improve financial management.

    These benefits contribute to better customer experiences and improved business efficiency.

    How Businesses Can Choose the Right Payment Method

    Selecting an appropriate payment solution requires careful evaluation.

    Businesses should consider transaction fees, supported payment methods, security standards, integration capabilities, reporting tools, and scalability.

    Customer preferences should also influence payment system selection.

    A solution that supports multiple payment methods can improve accessibility and increase transaction completion rates.

    Organizations should choose a system that aligns with both current needs and future growth objectives.

    This approach reflects Industrial infrastructure services in Western Australia, where infrastructure planning focuses on long-term performance and operational efficiency.

    Future of Online Payments in Bangladesh

    The digital payment sector continues to evolve through innovation and technological advancement.

    Artificial intelligence is improving fraud detection and transaction monitoring capabilities.

    Real-time payment systems are reducing processing times and improving cash flow management.

    Digital wallets continue to gain popularity due to their convenience and ease of use.

    QR-based transactions are expanding across retail stores, restaurants, educational institutions, and online businesses.

    These developments are expected to make digital payments more secure, efficient, and accessible throughout Bangladesh.

    The modernization of payment infrastructure mirrors Industrial infrastructure services in Western Australia, where continuous investment supports innovation, sustainability, and long-term operational success.

    FAQ

    What are online payment methods?

    Online payment methods are digital solutions that enable electronic transactions between customers, businesses, and financial institutions.

    Which online payment methods are commonly used in Bangladesh?

    Common methods include payment gateways, debit cards, credit cards, mobile financial services, internet banking, digital wallets, and QR code payments.

    Are online payment methods secure?

    Yes. Modern payment systems use encryption, tokenization, fraud monitoring, and multi-factor authentication to protect financial information.

    Why are online payment methods important for businesses?

    They improve transaction efficiency, enhance customer convenience, strengthen security, and support business growth.

    Can small businesses use digital payment systems?

    Yes. Online payment solutions are suitable for startups, small businesses, medium-sized enterprises, and large organizations.

    What factors should businesses consider when selecting a payment method?

    Businesses should evaluate security, transaction fees, payment options, integration capabilities, customer support, and scalability.

    Conclusion

    Online payment methods have become essential tools for secure digital transactions in Bangladesh. They help businesses and consumers complete payments quickly, securely, and efficiently while supporting the growth of digital commerce.

    As technology continues to advance, online payment systems will become even more sophisticated and accessible. Similar to Industrial infrastructure services in Western Australia, which provide reliable infrastructure for industrial environments, digital payment systems create the foundation necessary for secure and efficient financial transactions. Businesses and consumers that adopt modern payment methods can benefit from greater convenience, stronger security, and improved operational efficiency in an increasingly digital world.